

To quantify the potential impact of home loan fees, we assessed a sample of 110 different home loan products from 27 banks, non-banks and customer owned lenders and worked out what they charge across 34 specific fee types.
Below we list the mortgage fees and charges that could apply to your home loan, grouped according to when the fee is usually paid. Remember, fees can vary depending on the lender and loan product, but the minimum, maximum and average fees our analysis uncovered will give you a good idea of what to expect.
Summary of home loan fees charged by lenders
Upfront fees
- Loan application fee: A one-off cost between $150 and $750 to set up your home loan, also known as a loan processing fee or establishment fee.
- Document processing fee: The cost of preparing and processing documents for a new loan application. Typically ranging from $100 to $600.
- Search processing fees: Paid to your lender for the title search or any other searches related to your application (usually $50 per search).
- Valuation fee: Charged to cover the cost of conducting a valuation on your property – either online or by an external valuer. Expect a charge of $100-$300, or it may be dependent on the property location and value.
- Rate lock fee: A fee that is either a flat charge between $500-750 or a percentage of the home loan rate that is used to 'lock' in your fixed rate while the lender processes your home loan application. Rate locks will typically expire after 90 days. It will prevent your rate from increasing before settlement and if the lender's fixed rate drops, you'll still be able to get the lower rate.
- Security guarantee fee: Payable if a guarantor is added to the home loan for additional security – typically $200-$300.
- Additional security fee: A $100-$150 fee if the lender requires more than one security to secure the home loan.

| Upfront home loan fee | Minimum cost | Average cost | Maximum cost |
|---|---|---|---|
| Application fee | $150 | $397 | $750 |
| Document processing fee | $100 | $270 | $600 |
| Search processing fee | $50 | $50 | $50 |
| Valuation fee | $100 | $280 | $300 |
| Rate lock fee | $500 | $742 | $750 |
| Security guarantee fee | $200 | $246 | $300 |
| Additional security fee | $100 | $187 | $150 |
Fees paid upon settlement
- Settlement fee: A cost ranging from $150 to $300 for arranging settlement, organising the balance transfer to the seller and title transfer to you. This fee is payable regardless of whether the lender attends settlement or not.
| Fees paid upon settlement | Minimum cost | Average cost | Maximum cost |
|---|---|---|---|
| Settlement fee | $150 | $153 | $300 |
Building fees (progressive drawdown)
- Progressive drawdown fee: Usually found on construction home loans where the lender charges a fee to release each ‘progress payment’ to the borrower as the build progresses. A fee of $50-$100 typically applies each time funds are drawn down.
| Building fees | Minimum cost | Average cost | Maximum cost |
|---|---|---|---|
| Progressive drawdown fee | $50 | $207 | $100 |
Ongoing fees
- Monthly service fees: A monthly fee of $8 to $15 that covers the costs of administering your home loan. Also known as a loan service fee.
- Annual package fee: A yearly fee ($300 - $600) charged on a package home loan to bundle your mortgage with other financial products like a credit card or savings account.
- Late/missed payment fees: Charged on any overdue mortgage repayments, otherwise known as an arrears fee. Typically $15 to $25 per month.
| Ongoing fees | Minimum cost | Average cost | Maximum cost |
|---|---|---|---|
| Monthly service fees | $8 | $12 | $15 |
| Annual package fee | $300 | $326 | $600 |
| Late/missed payment fees | $15 | $21 | $25 |
Feature fees
- Redraw fees: Charged when redrawing extra payments made on your home loan – usually on fixed rate home loans. Usually $0 to $20 per redraw.
- Offset account fee: Charged to link your offset account to your home loan, including servicing. Costs $8 to $10 per month (or as a yearly figure), or as a one-time fee of $75 - $100.
- Portability fee: $150 - $300 fee for transferring your home loan to another property (i.e. when you buy a new home).
- Extra repayments fee: $0 to $20 charged if you pay your home loan off early or make early or extra repayments (usually on fixed rate home loans).
| Feature fees | Minimum cost | Average cost | Maximum cost |
|---|---|---|---|
| Redraw fee | $0 | $0 | $20 |
| Offset account fee | $8 | $10 | $10 |
| Portability fee | $150 | $300 | $300 |
| Extra repayments fee | $0 | $0 | $20 |
Exit fees
- Fixed rate break cost: A fee you pay if you repay a fixed rate home loan early or switch to a variable rate before your fixed term ends. Cost is dependent on the lender.
- Exit fees: Payable when exiting a home loan early (i.e. refinancing). Exit fees have been banned on new home loans from 1 July 2011. Fees vary based on the lender.
- Switching fee: A $100-$300 fee for refinancing to a new home loan or new lender.
- Mortgage discharge fee: Payable when you pay off your home loan in full and the lender discharges your mortgage. Typically $350 to $500 per mortgage.
| Exit fees | Minimum cost | Average cost | Maximum cost |
|---|---|---|---|
| Fixed rate break cost | $0 | $50 | $350 |
| Exit fee | $0 | $350 | $350 |
| Switching fee | $100 | $252 | $300 |
| Mortgage discharge fee | $350 | $360 | $500 |
Mortgage fees really matter on smaller loans
Katey Russo, Money.com.au Mortgage Broker
“As you pay down your loan, mortgage fees start to have a bigger impact on your overall costs. That’s because most standard loan fees are a fixed amount and you pay the same whether your loan is large or small.
A recent customer with around $220,000 left on their home loan was considering refinancing for a lower rate. We estimated they’d save about $22–$27 a month with the lower rate, but switching would cost around $800-$900. It would take roughly three years to make back the switching fees, which the client hadn’t appreciated. Fees are often an afterthought after rate, but in some cases they really matter.”
Katey Russo, Money.com.au Mortgage Broker
How mortgage fees impact your home loan
When you apply for a home loan, the interest rate isn’t the only cost to consider. Home loan fees can also impact what you pay.
To make sure you know how much you’ll be paying in fees and when, check your home loan’s Key Fact Sheet or schedule of fees for the full breakdown of fees and charges.
Lenders charge mortgage fees based on the type of home loan you choose and the service you require.
Broadly speaking, home loan fees may be charged:
- When you apply
- When the loan is finalised at settlement
- Throughout the loan term
- If you break a fixed rate home loan
- If you refinance to another lender
- If you require a guarantor
- When you repay the loan in full
Why do lenders charge home loan fees?
Lenders charge fees to cover the cost of processing and administering your home loan.
When you apply for a mortgage, a home loan specialist has to review your financial documents, conduct a credit check, organise a property valuation, process the legal documentation (e.g. sale agreement, deed of trust) and liaise with conveyancers until settlement day.
After that, your lender still has to manage your home loan account until it’s discharged (which can take up to 30 years or even 40 years with some lenders).
In short, these fees help lenders recover their operational costs, manage risk and provide flexibility or added features to borrowers.
Home loan fee cost comparison
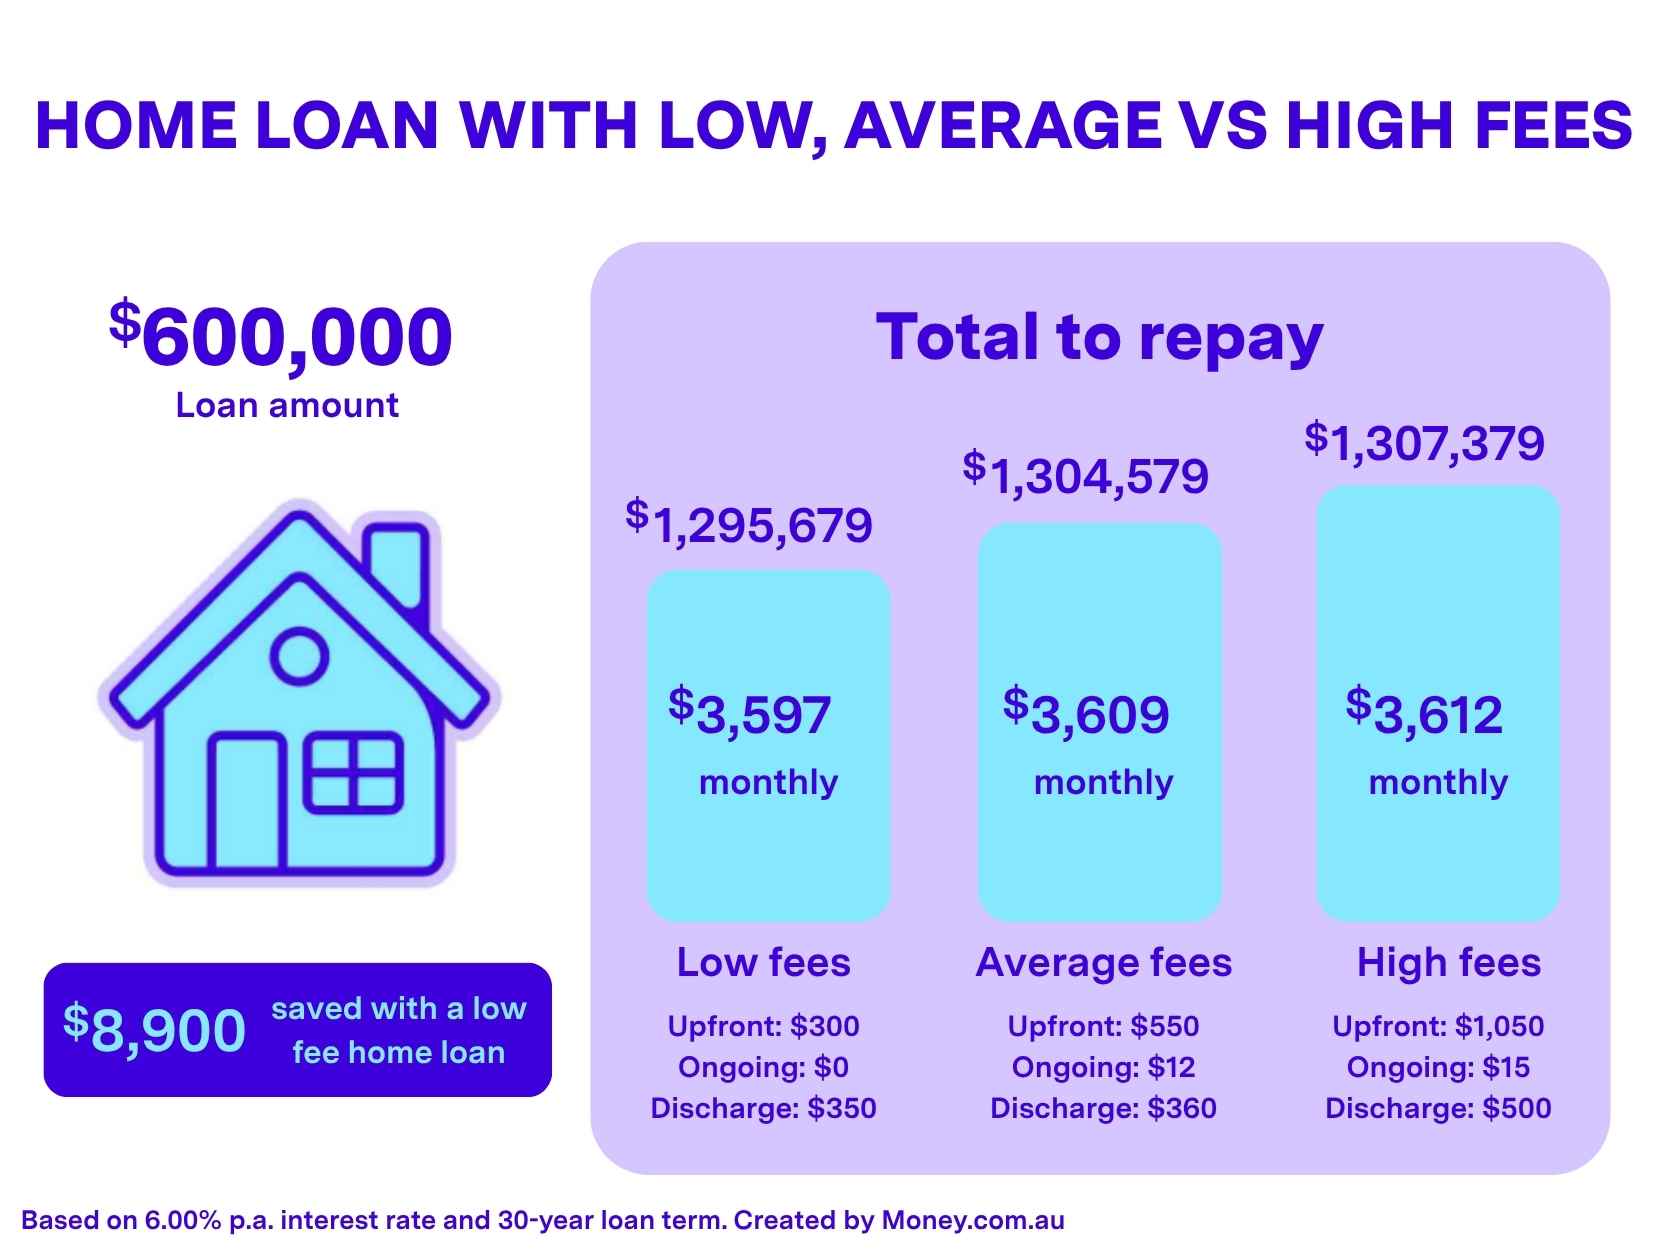
Home loan fees can have a significant impact on the overall cost of your mortgage. Here’s an example for a $600,000 home loan with a 6.00% interest rate over 30 years, with lower and higher fees.
Loan amount | |
Home loan with lower fees | $600,000 |
Home loan with average fees | $600,000 |
Home loan with higher fees | $600,000 |
Interest rate | |
Home loan with lower fees | 6.00% p.a. |
Home loan with average fees | 6.00% p.a. |
Home loan with higher fees | 6.00% p.a. |
Loan term | |
Home loan with lower fees | 30 years |
Home loan with average fees | 30 years |
Home loan with higher fees | 30 years |
Application fee | |
Home loan with lower fees | $150 |
Home loan with average fees | $397 |
Home loan with higher fees | $750 |
Settlement fee | |
Home loan with lower fees | $150 |
Home loan with average fees | $153 |
Home loan with higher fees | $300 |
Ongoing fees (monthly) | |
Home loan with lower fees | $0 |
Home loan with average fees | $12 |
Home loan with higher fees | $15 |
Discharge fee | |
Home loan with lower fees | $350 |
Home loan with average fees | $360 |
Home loan with higher fees | $500 |
Monthly repayments | |
Home loan with lower fees | $3,597 |
Home loan with average fees | $3,609 |
Home loan with higher fees | $3,612 |
Total fees payable | |
Home loan with lower fees | $650 |
Home loan with average fees | $5,230 |
Home loan with higher fees | $6,950 |
Total to repay on loan (principal, interest & fees) | |
Home loan with lower fees | $1,295,679 |
Home loan with average fees | $1,304,579 |
Home loan with higher fees | $1,307,379 |
Cost difference | |
Home loan with lower fees | |
Home loan with average fees | +$8,900 |
Home loan with higher fees | +$2,800 |
Fees as a percentage of the home loan amount | |
Home loan with lower fees | 0.11% |
Home loan with average fees | 0.87% |
Home loan with higher fees | 1.16% |
| Home loan with lower fees | Home loan with average fees | Home loan with higher fees | |
|---|---|---|---|
Loan amount | $600,000 | $600,000 | $600,000 |
Interest rate | 6.00% p.a. | 6.00% p.a. | 6.00% p.a. |
Loan term | 30 years | 30 years | 30 years |
Application fee | $150 | $397 | $750 |
Settlement fee | $150 | $153 | $300 |
Ongoing fees (monthly) | $0 | $12 | $15 |
Discharge fee | $350 | $360 | $500 |
Monthly repayments | $3,597 | $3,609 | $3,612 |
Total fees payable | $650 | $5,230 | $6,950 |
Total to repay on loan (principal, interest & fees) | $1,295,679 | $1,304,579 | $1,307,379 |
Cost difference | +$8,900 | +$2,800 | |
Fees as a percentage of the home loan amount | 0.11% | 0.87% | 1.16% |
When applying for a home loan or refinancing, look at the comparison rate, not just the interest rate. The comparison rate estimates the overall cost of a home loan per year, including fees.
Keep in mind, it’s based on a $150,000 loan over 25 years and might not reflect your personal scenario, but it can help highlight loans with higher fees.
Other home loan fees to consider
While we’ve covered the home loan fees charged by lenders, there are additional costs to consider:
Lender’s mortgage insurance (LMI)
If you’re buying a home and your deposit is less than 20% or if you’re refinancing and your loan-to-value ratio (LVR) exceeds 80%, you may have to pay lender’s mortgage insurance (LMI).
This is an insurance premium that covers the lender against the risk of you not being able to repay the loan. It’s calculated on a tiered scale, based on your LVR. You can add LMI to your home loan to avoid paying for it upfront, although this will increase your total interest costs.
Legal and conveyancing fees
When you buy a home, you’ll usually need to engage a conveyancer or solicitor to handle all the legal paperwork and processes, like transferring the property title to your name, etc.
Conveyancing fees can range between $1,200 and $2,400. These costs can vary depending on the complexity of the transaction and the state or territory you’re buying in.
Stamp duty
Stamp duty is a state government tax on property purchases and title transfers. It’s calculated as a percentage of the property’s value, ranging from 3-5%.
Stamp duty rates vary in each state or territory. Use our stamp duty calculator to estimate your costs. Stamp duty concessions or exemptions apply to eligible first home buyers in most states.
Don't forget about mortgage registration fees...
Don't forget about mortgage registration fees... Your state or territory government will charge you mortgage registration fees to register your mortgage on a property title.
This registers your property as the security on the home loan, allowing future buyers or lenders to check caveats on your home. Here are the current registration fees applicable for 2026/27:
New South Wales: $182.73 Victoria: $129.20 Queensland: $248.04 Western Australia: $225.10 South Australia: $204.00 Australian Capital Territory: $184.00 Tasmania: $167.58 Northern Territory: $181.00
How to get mortgage fees waived
While some fees are simply unavoidable, it’s worth researching lenders that offer fee waiver benefits. Or, engage a mortgage broker with knowledge on which lenders are likely to waive home loan fees for new customers.Katey Russo, Money.com.au Mortgage Broker
“A mortgage broker can generally negotiate with a lender to waive the home loan application fee and other fees. You can also ask the lender yourself to waive some fees or match the offer of a competitor to win your business. It’s all fair game. Lenders are generally more likely to waive home loan fees if you have a decent-sized home loan or good credit rating.”
Katey Russo, Money.com.au Mortgage Broker
Additional costs associated with owning property
Home loan fees are just one part of the picture – owning property comes with a few more costs to keep in mind.
Pest and building inspections
Before finalising a property purchase, pest and building inspections are strongly recommended to check for structural issues or pest infestations. These typically cost between $400 and $600, depending on the property size and location.
Home insurance
Otherwise known as building insurance, and often required by lenders that protects your house from damage due to events like fire, storms or theft. Expect to pay $800 to $2,000 per year, though costs vary based on property value, location and coverage level.
Council permits
If you’re planning renovations or structural changes, you'll likely need council approval, which involves application fees and sometimes inspections. Council permit fees can range from $200 to over $2,000, depending on the scope and complexity of the work.
Body corporate levies
If you own a unit, townhouse or duplex in a strata complex, you’ll need to pay body corporate levies for shared property maintenance. These levies usually range from $500 to $5,000 per quarter, based on common amenities and the building’s upkeep needs.
Utilities
Ongoing utility costs include council rates, water bills, and electricity or gas usage. Combined, these can cost homeowners $3,000 to $5,000+ per year, depending on property size, usage and local council rates.
Home maintenance
Regular maintenance like gutter cleaning, lawn care or minor repairs helps prevent long-term damage. Basic maintenance tasks can cost $500 to $2,000+ annually, especially if you hire professionals.