Compare home loan cashback offers from our lender panel and get expert help working out if refinance cashback will be worth it for you.


Home loan rates are high (and heading higher) and borrowers are shopping around in their droves to find the best deal. The table below shows a selection of lenders looking to capitalise with home loan cashback offers for eligible borrowers.
Lender | IMB Bank |
|---|---|
Cashback amount |
|
Minimum loan | $250,000 |
Max LVR | 80% |
Available for |
|
Offer expiry | Until further notice |
Key catch | Clawback clause means 50% of cashback will be lost if the loan is closed within 12 months |
Lender | BankVic |
Cashback amount |
|
Minimum loan | $350,000 |
Max LVR | 80% |
Available for |
|
Offer expiry | Until further notice |
Key catch | Only for emergency, health and government workers and their immediate families. |
Lender | ME Bank |
Cashback amount |
|
Minimum loan | $700,000 |
Max LVR | 80% |
Available for |
|
Offer expiry | Apply by 28 February 2027 |
Key catch | Excludes refinances from other BOQ Group lenders |
Lender | ANZ |
Cashback amount |
|
Minimum loan | $250,000 |
Max LVR | Not disclosed |
Available for |
|
Offer expiry | Until further notice |
Key catch | Not available with the Australian Government 5% Deposit Scheme or an ANZ LMI waiver |
Lender | Border Bank |
Cashback amount |
|
Minimum loan | $300,000 |
Max LVR | 80% |
Available for |
|
Offer expiry | Until further notice |
Key catch | Requires three consecutive salary deposits to an Easy Access account |
Lender | Police Bank |
Cashback amount |
|
Minimum loan | $300,000 |
Max LVR | 80% |
Available for |
|
Offer expiry | Until further notice |
Key catch | Requires three consecutive salary deposits to an Easy Access account |
Lender | Greater Bank |
Cashback amount |
|
Minimum loan | $250,000 |
Max LVR | 80% |
Available for |
|
Offer expiry | Until further notice |
Key catch | Lower level of cashback available if you don’t apply online |
Lender | Newcastle Permanent |
Cashback amount |
|
Minimum loan | $250,000 |
Max LVR | 80% |
Available for |
|
Offer expiry | Until further notice |
Key catch | Online applications only |
Lender | BOQ |
Cashback amount |
|
Minimum loan | $250,000 |
Max LVR | 80% |
Available for |
|
Offer expiry | Apply by 28 February 2027 |
Key catch | Branch applications only |
Lender | Credit Union SA |
Cashback amount |
|
Minimum loan | $300,000 |
Max LVR | 80% |
Available for |
|
Offer expiry | Until further notice |
Key catch | Restricted to borrowers connected with the SA education community |
Lender | ME Bank higher-LVR offer |
Cashback amount |
|
Minimum loan | $400,000 |
Max LVR | 80%–95% |
Available for |
|
Offer expiry | Until further notice |
Key catch | Only available for high LVR loans if you are paying for lender’s mortgage insurance |
Lender | P&N Bank |
Cashback amount |
|
Minimum loan | $250,000 |
Max LVR | 80% |
Available for |
|
Offer expiry | Until further notice |
Key catch | Only for eligible essential-services workers in WA; cannot be combined with P&N’s LMI waiver |
Lender | NRMA |
Cashback amount |
|
Minimum loan | n/a |
Max LVR | n/a |
Available for |
|
Offer expiry | Apply by 19 October 2026 |
Key catch | It's a pre-loaded gift card, as opposed to cold, hard cash |
| Lender | Cashback amount | Minimum loan | Max LVR | Available for | Offer expiry | Key catch |
|---|---|---|---|---|---|---|
IMB Bank |
| $250,000 | 80% |
| Until further notice | Clawback clause means 50% of cashback will be lost if the loan is closed within 12 months |
BankVic |
| $350,000 | 80% |
| Until further notice | Only for emergency, health and government workers and their immediate families. |
ME Bank |
| $700,000 | 80% |
| Apply by 28 February 2027 | Excludes refinances from other BOQ Group lenders |
ANZ |
| $250,000 | Not disclosed |
| Until further notice | Not available with the Australian Government 5% Deposit Scheme or an ANZ LMI waiver |
Border Bank |
| $300,000 | 80% |
| Until further notice | Requires three consecutive salary deposits to an Easy Access account |
Police Bank |
| $300,000 | 80% |
| Until further notice | Requires three consecutive salary deposits to an Easy Access account |
Greater Bank |
| $250,000 | 80% |
| Until further notice | Lower level of cashback available if you don’t apply online |
Newcastle Permanent |
| $250,000 | 80% |
| Until further notice | Online applications only |
BOQ |
| $250,000 | 80% |
| Apply by 28 February 2027 | Branch applications only |
Credit Union SA |
| $300,000 | 80% |
| Until further notice | Restricted to borrowers connected with the SA education community |
ME Bank higher-LVR offer |
| $400,000 | 80%–95% |
| Until further notice | Only available for high LVR loans if you are paying for lender’s mortgage insurance |
P&N Bank |
| $250,000 | 80% |
| Until further notice | Only for eligible essential-services workers in WA; cannot be combined with P&N’s LMI waiver |
NRMA |
| n/a | n/a |
| Apply by 19 October 2026 | It's a pre-loaded gift card, as opposed to cold, hard cash |
Our analysis shows Greater Bank’s cashback deal, combined with the low rates and fees on its Great Rate Home Loan, offers the biggest potential overall benefit to customers.
We assessed each of the cashback offers we could find, combined with that lender’s lowest owner-occupier variable rate, plus establishment and ongoing fees, and calculated the net outcome over a two-year period for three different loan amounts.
The result shows that the biggest cashback is not necessarily the best deal. Home loan rates and fees have a massive impact on the overall outcome.
| Lender and product | Interest rate | Comparison rate* | Cashback | Lender fees | Estimated two-year cost |
|---|---|---|---|---|---|
| Greater Bank Great Rate Home Loan | 5.84% p.a. (variable) | 5.85% p.a. | $3,000 | $180 | $83,236 |
| Border Bank Customs Value | 5.84% p.a. (3-yr fixed) | 5.99% p.a. | $3,000 | $974 | $84,030 |
| Police Bank Police Value | 5.84% p.a. (3-yr fixed) | 5.99% p.a. | $3,000 | $974 | $84,030 |
| IMB Budget Home Loan | 5.99% p.a. (variable) | 6.02% p.a. | $4,000 | $799 | $85,100 |
| Newcastle Permanent Real Deal – Special | 5.94% p.a. (variable) | 5.98% p.a | $3,000 | $595 | $85,147 |
| ME Bank variable home loan | 5.99% p.a. (variable) | 6.01% p.a. | $3,000 | $150 | $85,451 |
| BOQ owner-occupier variable home loan | 6.03% p.a. (variable) | 6.18% p.a. | $2,000 | $690 | $87,589 |
| Lender and product | Interest rate | Comparison rate* | Cashback | Lender fees | Estimated two-year cost |
|---|---|---|---|---|---|
| Greater Bank Great Rate Home Loan | 5.84% p.a. (variable) | 5.85% p.a. | $3,000 | $180 | $54,550 |
| Police Bank Police Value | 5.84% p.a. (3-yr fixed) | 5.99% p.a. | $3,000 | $974 | $55,344 |
| Border Bank Customs Value | 5.84% p.a. (3-yr fixed) | 5.99% p.a. | $3,000 | $974 | $55,344 |
| Newcastle Permanent Real Deal – Special | 5.94% p.a. (variable) | 5.98% p.a | $3,000 | $595 | $55,963 |
| IMB Budget Home Loan | 5.99% p.a. (variable) | 6.02% p.a. | $3,000 | $799 | $56,666 |
| BOQ owner-occupier variable home loan | 6.03% p.a. (variable) | 6.18% p.a. | $2,000 | $690 | $57,956 |
| Lender and product | Interest rate | Comparison rate* | Cashback | Lender fees | Estimated two-year cost |
|---|---|---|---|---|---|
| Greater Bank Great Rate Home Loan | 5.84% p.a. (variable) | 5.85% p.a. | $3,000 | $180 | $32,102 |
| Newcastle Permanent Real Deal – Special | 5.94% p.a. (variable) | 5.98% p.a | $2,500 | $595 | $33,116 |
| Border Bank Customs Value | 5.84% p.a. (3-yr fixed) | 5.99% p.a. | $2,000 | $974 | $33,396 |
| Police Bank Police Value | 5.84% p.a. (3-yr fixed) | 5.99% p.a. | $2,000 | $974 | $33,396 |
| IMB Budget Home Loan | 5.99% p.a. (variable) | 6.02% p.a. | $2,000 | $799 | $34,119 |
| BOQ owner-occupier variable home loan | 6.03% p.a. (variable) | 6.18% p.a. | $2,000 | $690 | $34,250 |
Money.com.au compared the estimated two-year cost of the home loan cashback offers available from lenders we found that were currently offering cashback. We excluded lenders with limited eligibility criteria from the analysis.
We calculated the interest payable in the loan over two years, plus the lender’s establishment, settlement, monthly and any ongoing fees, then deducted the cashback available at each loan balance.
The calculation is based on an owner-occupier refinancing to a fixed or variable rate home loan with principal and interest repayments, a 60% LVR and a remaining loan term of 25 years.
The assessment does not include fees that would likely apply to options equally, including exit fees charged by the current lender or government fees that may apply when switching home loans. Just bear in mind that these fees could impact the net outcome, depending on the situation. The assessment does not factor in loan features.
Rates and offer details were checked on 1 October 2026.
Home loan cashback

Almost 4 in 5 home loan borrowers (79%) say cashback would make them more likely to switch lenders. But options are limited, with only around a dozen lenders offering cashback to eligible new customers., according to our analysis
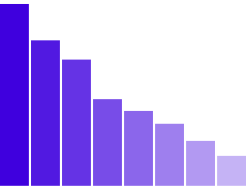
On a $750,000 loan, our analysis shows a $3,000 cashback would be wiped out in around 1.7 years if your interest rate is 0.25 percentage points higher than you could get elsewhere.
“A good cashback deal is the one you get on a loan you’d still choose if the cashback wasn’t there.”
Customers regularly ask our home loan brokers about cashback offers. The conversation usually starts as ‘can I get cashback?’ but a far more useful question to ask is 'should I get cashback?'
The reality is, cashback is worthwhile for some customers and it’s a great bonus on top of the broader benefits of refinancing. But it’s absolutely not guaranteed to be the best option.
Here are the factors that will determine whether a cashback offer will leave you better or worse off.
How much cashback are you actually getting? The lender’s headline cashback offer may not be what you end up getting, as it often depends on your loan size. In the case of Greater Bank, the cashback also depends on how you apply for the loan, with $500 extra cashback offered for online applications versus lender-assisted applications.
What’s the interest rate on the loan? Paying a higher home loan rate than you can get elsewhere is usually not a good idea, even if you get cashback. For example, a rate of 6.25% versus 6.00% on a $750k loan with a 25-year term would mean roughly an extra $1,875 in interest costs in the first year alone. In that case, the cashback benefit would be wiped in around 1.7 years.
How much are the switching fees? As a rule of thumb, we tell customers to budget for around $1,000 in fees when you refinance. It’s a slightly crude number and won’t apply universally, but taking whatever the cashback offer is and subtracting $1,000 for fees is often realistic. That said, you’ll generally have switching fees whether you move to a loan with or without cashback.
What’s your loan size? On larger loan sizes you can often earn more cashback. But you need to be very careful, as the impact of a higher interest rate will be amplified in larger loan balances. This is exactly why lenders offer more cashback on larger loan sizes. They make more money in interest on those loans.
How will you use the money? Cashback works best if you put the money back into the home loan, either as a lump sum repayment or funds you keep in your offset account. Spending it on a new TV is fine too (we’re not here to judge), but if you put $3,000 cashback back into your loan and left it there, you would save around $10,300 in interest over 25 years on a $750,000 home loan at 6% p.a.
Would you be better off staying put? A lot of mortgage brokers won't tell you this, but in some cases, not switching is the best outcome. Refinance costs can be significant and even with a broker's help, there's a bit of work involved. If you think you can get a better deal, ask your current lender if they'll match it. They probably won't give you cashback, but you might get a better interest rate, which is often just as good.

How long are you planning to keep the loan for?
We don’t recommend this strategy to clients, but if you’re choosing a loan for the cashback and the rate is not competitive, you really need to be setting a reminder to review it in a couple of years at the latest. You’ll have more switching costs to pay then too, but paying a higher interest rate for longer would likely be a much worse outcome. Just watch out for lenders who claw back some of the cashback if you jump ship soon after receiving it.
| Refinancing with a lower rate | Refinancing with cashback | |
|---|---|---|
Loan amount | $750,000 | $750,000 |
Interest rate | 6.00% | 6.25% |
Cashback | $0 | $3,000 |
Monthly repayments | $4,832 | $4,948 (+$116) |
Time it would take for interest savings to cancel out cashback | 20 months | - |
Michael Burgess, Money.com.au Expert Mortgage Broker
"Cashback can give good short-term value, but it don't always work out beyond the first year or two. The risk is the offer gets you in the door, but if something happens to your finances and you can't refinance again, you might be stuck on a higher rate.
Our priority for clients is always on the loan fundamentals, with cashback as a secondary factor.
As an example, a recent client came to us looking to refinance $1 million in investment lending, ideally with cashback.
We looked at a lender offering up to $3,500 cashback at the time, but the interest rate was higher than several lenders with no cashback offer.
Luckily we were able to negotiate preferential pricing with a non-cashback lender, and structured the deal so the client was clearly in a stronger overall position both in the short and long term.”
Michael Burgess, Money.com.au Expert Mortgage Broker
This kind of perk is more commonly associated with rewards credit cards, but a relatively new innovation in the home loan market is lenders offering reward points to customers who sign up. If you're considering this kind of offer, it's worth checking what the points would be worth when converted to gift cards. That will give you a rough idea of the offer's value compared to getting cashback.
Here are the current home loan rewards points offers available:
Discounted home loan interest rates are another carrot being sometimes dangled in front of refinancers. The catch is generally that the lower rate is for a limited period only. Some providers offer refinancers an ongoing discount that applies progressively as you pay off the loan (i.e. every year you get an additional discount on your rate). Unloan (backed by CommBank) and Athena Home Loans are among the Australian lenders with this kind of offer.
Instead of offering cashback, some lenders simply waive all fees on selected home loans products to attract new customers. In some cases, the waiver just covers just the fees on the lender’s own product, but some lenders will cover the exit fees changed by your current lender too. So it effectively functions as cashback but the money is limited to being used to cover switching fees.
No, cashback on home loans is considered a rebate or discount, not taxable income, according to the ATO. You won’t need to declare it as earnings, and it won’t affect your taxable income, but always confirm with a financial advisor for your situation.
Generally yes, but this depends on the lender and it's worth checking the cashback offer T&Cs, as some lenders do exclude broker loans.
Yes, some lenders may offer cashback alongside other incentives like discounted interest rates, waived fees, or rewards points. However, not all promotions can be combined. Check with your lender or mortgage broker to confirm whether the cashback offer stacks with other deals or excludes certain benefits.
Most lenders pay cashback within 60 to 90 days after settlement, according to Money.com.au analysis. Some also require the loan to settle within a set period (i.e. 120 days from application). To avoid delays or potential disappointment, confirm the payment timeframe and conditions with your lender or mortgage broker before applying.
Many lenders extend cashback offers to both owner-occupier and investment loans, but some may limit offers exclusively to one category. Always verify eligibility, loan purpose, and any differences in terms based on loan type.
Yes, some lenders specifically offer cashback first-home buyer loans, while others simply include all purchases, which would include first-home buyers. However, some offers are specifically for refinancers with an existing loan.
A key point here is that the eligibility on most cashback offers requires you to have an LVR of 80% or less, or a 20% home deposit in other words, which is always a big ask for first home buyers.
Yes, once received, cashback funds can be used however you choose, including the likes of stamp duty, moving costs or legal fees. But because the cashback payout usually happens after settlement (typically 60-90 days), you’ll need to cover initial expenses upfront yourself and then use the cashback to replenish your savings.
Michael Burgess and Merlan Bayani were wonderful in helping us with the entire refinance process. Not only they secured a great home loan rate, they also worked extreme fast, thorough and kept on top of their communication throughout the process. Thank you both for your amazing work!
Nick from Money was absolutely amazing! He answered all of our questions, and worked through different lending scenarios with us. He was honest, down to earth,and especially great at communicating. Nick always responded quickly but thoroughly and it was obvious he has a great deal of knowledge in his field. Couldn’t have asked for better, and have already used his services a second time.
Michael and Merlan were very attentive and responsive throughout our home purchase process. They helped us secure a great mortgage rate and even offered a rebate for using their services. Highly recommend!
Thank you, Merlan and Katey, for your incredible support and guidance throughout my home-buying journey. You made the process simple, stress-free, and were always there to help whenever I needed it. I truly appreciate all your hard work and would highly recommend your services!
Katey & Merlan were extremely knowledgeable and helpful in sourcing us a home loan. Made the entire process extremely easy. Katey often worked after hours to push things through which was greatly appreciated. Would trust Money.com with any loan applications as we certainly will use them again.
I was looking for a refinance It was tricky to get a best rate with offset account. Yang Qiu helped us for getting the perfect rate with the best options we could get.
I honestly can’t recommend Nick enough. He made what could have been a really stressful process feel so easy. He was always quick to answer my questions, explained everything in a way that actually made sense, and kept me updated every step of the way. Nothing was ever too much trouble, and I always felt like he genuinely had our best interests at heart. Thanks so much, Nick. We really appreciate everything you did for us!
Exceptional customer service from a fantastic team. Katey and Merlan made the entire process very simple and stress free. They both went above and beyond to help me out, and their efficiency and support were way above expectations. Definitely a great option for broker services, I highly recommend Money.com.au!! Thank you :)
Thank you so very much. Katey, Merlan and the team at money.com were extremely efficient, friendly and made our refinance smooth and hassle free. They made sure we get the best deal possible. Every communication was transparent with no hidden information. Highly recommend them if anyone looking to refinance. God bless you all richly!! Melieta and Jaison
Katey and Desiree have been very helpful and very responsive to all my questions and emails, even late in the evening.
Very prompt service and helpful all the way through
I can’t recommend my broker highly enough. I made the decision to proceed with Nick Burgess on Tuesday afternoon and by Friday morning my finance has been approved – an incredible turnaround time. As a first-home buyer, the process felt overwhelming at times, with a lot of documentation, questions, and back-and-forth communication required. Throughout every step, my broker was professional, responsive, and always available to answer my questions. Their communication was exceptional, keeping me informed at every stage and making sure I understood exactly what was happening. Most importantly, they gave me confidence throughout the entire process. Buying your first property is a huge milestone, and having someone knowledgeable, proactive and genuinely invested in achieving the best outcome for me made all the difference. Thank you for making what could have been a stressful experience feel smooth and manageable. I wouldn’t hesitate to recommend your services to anyone looking for a mortgage broker, especially first-home buyers.
We were delighted with the warm, helpful, fully informed and friendly advice received. Came away fully satisfied all our questions had been answered FULLY. Some were even ANTICIPATED. Nick KNOWS HIS STUFF
So our agent Nick was what made this experience easy and stress free. Refinancing is stressful, but Nick turned around our package very quickly and on a decent rate in a competitive climate. He was responsive through out the process and always clarified any of our silly questions, demonstrating his patience and care with respect to customer service. We’ll be hitting him in a few years time when our current rate expires!
We had an outstanding experience working with Michael Burgess at money.com.au. From start to finish, he was professional, responsive, and genuinely invested in helping us achieve the best outcome. Michael secured us a great mortgage and, more importantly, put together a clear and well thought out plan for transitioning into our next home. We were navigating a bridging loan, and he made the entire process feel smooth and straightforward. Nothing was ever too much trouble, and he explained everything in a way that gave us real confidence at every step. It honestly could not have been easier. Highly recommend Michael to anyone looking for expert guidance and a seamless experience.
Straight to the point information. No beating around the bush if you can borrow money or refinance. Very helpful. Thank you very much 👍
I had a really great experience with money.com. The entire process was super straightforward and easy to follow, which made everything feel stress-free from start to finish. The customer service was incredible. The team was friendly, helpful, and always willing to answer any questions I had. They were also very responsive, which I really appreciated. On top of that, the pricing was excellent and very competitive. I would definitely recommend them to anyone looking for a smooth and reliable experience.
Explained everything really well,treated me like I mattered an just got the job done👍
Staff are very professional and helpful.
Great service and very helpful
Home loan comparison rates are calculated based on a loan amount of $150,000 repaid over a 25-year term with monthly repayments. The comparison rates only apply to the examples given. Different loan amounts and terms will result in different comparison rates. Costs such as redraw fees or early repayment fees and cost savings such as fee waivers are not included in the comparison rate but may influence the cost of the loan. Check with the provider for full loan details, including rates, fees, eligibility and terms and conditions to make sure the product is right for you.
General information only The information on this page is general in nature and has been prepared without considering your objectives, financial situation or needs. You should consider whether the information provided and the nature of any home loan product is suitable for you and seek independent financial advice if necessary.
We are not providing you with a recommendation or suggestion about a particular home loan. You should read the relevant disclosure statements or other offer documents before deciding whether to apply for or continue to use a particular product.
What products, features and information are shown We show product information from our providers in our lending panel and no not include all lenders in the market. Our product comparisons may not compare all home loan features and attributes relevant to you.
Product information, such as interest rates, fees and charges, is subject to change without notice. Before acting on any information, you should confirm the relevant product information with the lender.
How home loans are sorted and filtered by default When results load initially in the main comparison table on this page, we show relevant loans from our sponsored partners first, then all loans on our lender panel, starting with the lowest relevant rate available from each of Australia's top 10 largest lenders first (top 10 is according to APRA, based on total value of loans per lender). We know these are the rates our customers are most interested in seeing. After these initial results, we show all products from our lender panel, sorted as follows:
Home loan products listed in our tables are available through a mortgage broker. Mortgage brokers cannot offer loans from every provider and there may be more suitable loans for your personal circumstances.
Mortgage brokers are not authorised by Money Pty Ltd's Australian Credit Licence and operate under their own Australian Credit Licence, or as a credit representative of another Australian Credit Licensee. Mortgage brokers can make recommendations about home loan products that may suit your objectives, financial situation and needs.
Partner lenders with loans marked as ‘sponsored’ may pay a commission to Money.com.au if you click to visit their website.
If you get help from a mortgage broker as a result of visiting this page, we may earn a commission. Learn more about how we make money.