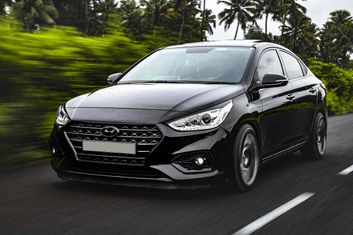
Hyundai finance options at a glance
- Finance for Hyundai i30, Sante Fe, Tucson, Kona, IONIQ 5 and more
- Low rate secured car loans
- Hyundai commercial finance options
- Novated lease for Hyundai available
- Borrow up to $150,000
- Fixed or variable interest rate
- Finance terms from 1 - 7 years
- Flexible repayment options
- Pre-approval available

Compare car loan rates by category
Lowest car loan rates (all loan types)
| Loan | Interest rates from | Comparison rates from^ | Loan amounts |
|---|
Lowest EV/green car loan rates
| Loan | Interest rates from | Comparison rates from^ | Loan amounts |
|---|
Lowest fixed car loan rates
| Loan | Interest rates from | Comparison rates from^ | Loan amounts |
|---|
Lowest variable car loan rates
| Loan | Interest rates from | Comparison rates from^ | Loan amounts |
|---|
Hyundai finance rates compared
Compare car loan interest rates for different Hyundai models to estimate your monthly repayments.
Hyundai model | Venue (base) |
|---|---|
Estimated cost | $22,500 |
Monthly repayments (6% p.a. interest) | $435 |
Monthly repayments (8% p.a. interest) | $456 |
Monthly repayments (10% p.a. interest) | $478 |
Hyundai model | i30 (hatch base) |
Estimated cost | $24,000 |
Monthly repayments (6% p.a. interest) | $464 |
Monthly repayments (8% p.a. interest) | $487 |
Monthly repayments (10% p.a. interest) | $509 |
Hyundai model | Kona (base) |
Estimated cost | $32,500 |
Monthly repayments (6% p.a. interest) | $628 |
Monthly repayments (8% p.a. interest) | $659 |
Monthly repayments (10% p.a. interest) | $691 |
Hyundai model | Tucson (FWD) |
Estimated cost | $39,100 |
Monthly repayments (6% p.a. interest) | $756 |
Monthly repayments (8% p.a. interest) | $793 |
Monthly repayments (10% p.a. interest) | $831 |
Hyundai model | Staria (Load 2S - 2.2D Liftback) |
Estimated cost | $46,740 |
Monthly repayments (6% p.a. interest) | $904 |
Monthly repayments (8% p.a. interest) | $948 |
Monthly repayments (10% p.a. interest) | $993 |
Hyundai model | Sante Fe (7 seat - 2WD) |
Estimated cost | $53,000 |
Monthly repayments (6% p.a. interest) | $1,025 |
Monthly repayments (8% p.a. interest) | $1,075 |
Monthly repayments (10% p.a. interest) | $1,126 |
Hyundai model | Sonata (N Line) |
Estimated cost | $55,500 |
Monthly repayments (6% p.a. interest) | $1,073 |
Monthly repayments (8% p.a. interest) | $1,125 |
Monthly repayments (10% p.a. interest) | $1,179 |
Hyundai model | IONIQ 6 (2WD - 53 kWh) |
Estimated cost | $66,500 |
Monthly repayments (6% p.a. interest) | $1,286 |
Monthly repayments (8% p.a. interest) | $1,348 |
Monthly repayments (10% p.a. interest) | $1,413 |
Hyundai model | Palisade (Elite 7-seat) |
Estimated cost | $66,800 |
Monthly repayments (6% p.a. interest) | $1,291 |
Monthly repayments (8% p.a. interest) | $1,354 |
Monthly repayments (10% p.a. interest) | $1,419 |
Hyundai model | IONIQ 5 (2WD - 63kWh) |
Estimated cost | $69,800 |
Monthly repayments (6% p.a. interest) | $1,349 |
Monthly repayments (8% p.a. interest) | $1,415 |
Monthly repayments (10% p.a. interest) | $1,483 |
| Hyundai model | Estimated cost | Monthly repayments (6% p.a. interest) | Monthly repayments (8% p.a. interest) | Monthly repayments (10% p.a. interest) |
|---|---|---|---|---|
Venue (base) | $22,500 | $435 | $456 | $478 |
i30 (hatch base) | $24,000 | $464 | $487 | $509 |
Kona (base) | $32,500 | $628 | $659 | $691 |
Tucson (FWD) | $39,100 | $756 | $793 | $831 |
Staria (Load 2S - 2.2D Liftback) | $46,740 | $904 | $948 | $993 |
Sante Fe (7 seat - 2WD) | $53,000 | $1,025 | $1,075 | $1,126 |
Sonata (N Line) | $55,500 | $1,073 | $1,125 | $1,179 |
IONIQ 6 (2WD - 53 kWh) | $66,500 | $1,286 | $1,348 | $1,413 |
Palisade (Elite 7-seat) | $66,800 | $1,291 | $1,354 | $1,419 |
IONIQ 5 (2WD - 63kWh) | $69,800 | $1,349 | $1,415 | $1,483 |

We surveyed more than 1,000 Australian drivers to find out if they’d buy their current car again (either the same make or model).
Nearly two-thirds (65.4%) said yes, they love their current car. Among these satisfied drivers, Hyundai ranked third, with 11.4% driving one – behind only Toyota and Mazda. That’s notably higher than Hyundai’s year-to-date market share of 6.4% for new car sales as of November 2025, according to the FCAI.
Our data also reveals that one in three Australians (33%) have bought a car brand influenced by childhood familiarity with the company. Hyundai ranks fourth at 8%, coming behind Toyota (36%), Mazda (13%) and Holden (9%).
Types of Hyundai finance options available
Secured loan
Financing your Hyundai with a secured car loan is a popular option because the car serves as security, reducing the lender's risk. If you fail to repay the loan, the lender can take back the car and sell it to cover the remaining debt. Loan terms usually range from 1 to 7 years, and you can choose between fixed or variable interest rates.
Unsecured loan
An unsecured personal loan is similar to a car loan but doesn’t require the Hyundai to be used as security. Since the loan isn’t secured by the car, lenders typically charge higher interest rates to cover the additional risk. Aside from this, unsecured loans work much like car loans.
Novated lease
A novated lease allows you to finance a new or used Hyundai through your employer. This type of lease provides substantial tax advantages, particularly for electric vehicles, when compared to a traditional car loan. With a novated lease, you can cover the cost of your Hyundai and its running expenses (like charging, car insurance, etc.) using your pre-tax income. Additionally, you’ll receive a GST discount on both the vehicle and its running costs.
For eligible Hyundai models (like the IONIQ and Kona), novated leases may also be exempt from fringe benefits tax (FBT). This can result in significant savings compared to other financing options in Australia, provided the car’s value is below the luxury car tax (LCT) threshold.
Finance lease
A finance lease for a Hyundai enables a business to lease the vehicle for a set period, making regular payments for its use. In this arrangement, the lender purchases the Hyundai on behalf of the business.
At the lease’s end, the business has the option to buy the car, extend the lease or return it. Finance leases can offer tax advantages, as lease payments may be deductible, and provide a way for businesses to access a vehicle without the initial expense of purchasing it.
Chattel mortgage
A chattel mortgage is a financing option where a business borrows money to buy the vehicle, using the Hyundai as security for the loan. The business immediately owns the car, but the lender holds a mortgage on it until the loan is fully repaid.
This option lets businesses claim GST on the vehicle’s purchase price and potentially deduct interest and depreciation costs as business expenses. It’s ideal for businesses that want to own their Hyundai from day one while spreading the cost over time.
Hyundai green loan
If you're thinking about a vehicle from Hyundai's electric range (such as the Kona or IONIQ), you might qualify for a green car loan. This type of financing is offered by some lenders for environmentally-friendly purchases. In most cases, a green loan works like a secured car loan but may offer advantages like a lower interest rate and reduced fees.
Hyundai dealer finance
Like many manufacturers, Hyundai offers direct financing to its customers, including a fixed-rate car loan called the "Hyundai Guaranteed Future Value."
With this financing, you can either make a deposit upfront or opt for a balloon payment, which reduces your regular repayments but requires you to pay an agreed amount at the end of the contract. Hyundai offers loan terms ranging from 24 to 48 months, with an expected annual mileage between 10,000 and 40,000 km. At the end of the loan, you have the option to trade in, keep or return the vehicle.
Hyundai will determine the Guaranteed Future Value (GFV) of the car at the end of the loan. If you choose to return it, Hyundai will pay you the agreed GFV, which will be applied toward your final payment, provided certain conditions and kilometre limits are met.
Hyundai also offers personal car finance through its dealers. However, when considering dealer finance, it's important to note that it’s often marketed as the most convenient option, but it might not always be the best deal.
As advised by the Australian Federal Government’s Moneysmart website, it's wise to shop around for the best financing option. This gives you access to a wider range of loans and leases, which can be approved just as quickly as dealer finance.
How to get the best Hyundai finance deal
While the advertised car loan interest rate will be a key factor in the overall cost of your Hyundai finance, there are other aspects to consider when seeking the best deal:

Ongoing finance rate
Compare finance options from banks, credit unions, specialist lenders and Hyundai’s dealer finance. Keep in mind that some dealer finance offers might start with a low introductory rate, but may increase after a set period. If you choose Hyundai dealer finance, look for a competitive rate that remains consistent throughout the entire loan term.

Fees
Some lenders may charge application fees and ongoing costs that can add up quickly. Be mindful of additional fees, such as late payment charges or penalties for paying off your Hyundai loan early. Regardless of how you finance your Hyundai, expect some fees, so ensure they’re minimal and don’t outweigh the benefits of a low interest rate.

Finance term
Consider the length of your loan term carefully. While a longer term can lower your monthly repayments, it typically results in higher overall interest costs. For instance, if you finance a Hyundai Tucson (FWD) priced at $39,100 with an interest rate of 8% p.a., you’ll pay an additional $3,623 in interest over a 7-year term compared to a 5-year term.

Repayment flexibility
Having the option to make extra repayments without penalties gives you the flexibility to pay off your loan early, potentially reducing the total interest you pay over time and saving you money. It’s also worth considering whether the loan allows you to choose between weekly, fortnightly or monthly repayments to best fit your budget.
Eligibility for Hyundai finance
The eligibility criteria for a Hyundai car loan will differ depending on the lender, but generally, you will need to:
- Be at least 18 years of age
- Hold Australian citizenship or permanent residency
- Have a steady income that can support loan repayments
- Meet other credit criteria set by the lender, including your credit score, expenses and existing debt
How to apply for Hyundai finance

To apply for Hyundai finance in Australia, you’ll need to follow these steps:
- Compare a range of quotes from various finance providers.
- Choose the deal that best suits your needs or use a car loan broker who can help.
- Submit your application to your lender of your choice.
- Provide the necessary documents to support your application, such as bank statements and payslips.
- Wait for your application to be reviewed by the lender.
If approved, you will receive car loan pre-approval for a certain amount, allowing you to shop for a Hyundai with a budget in mind. Alternatively, if you have already found a Hyundai model to buy, the lender will give final loan approval.
Some providers offer same-day approval on Hyundai finance, so you can apply and be approved for a car loan quickly and easily.

Ready to get a great deal on your Hyundai finance?
There's no obligation and checking rates and offers with a partner broker won't impact your credit score.