Can you get health insurance with no waiting period?
It’ll depend on the type of cover you take out:

Hospital cover (generally, NO)
All hospital policies have a minimum waiting period of two months for most treatments, including procedures such as joint replacements and cataract surgery, provided the condition is new. Pre-existing conditions and obstetrics (pregnancy and birth) have longer waiting periods of 12 months. If you’re switching to the same level of cover (or lower) with a different provider you won’t have to re-sit waiting periods.

Extras cover (YES, in some cases)
Many health funds waive certain waiting periods on extras cover such as dental, optical, and physiotherapy to attract new members. These offers are often promoted as “2- and 6-month waiting periods waived on extras” but may come with conditions, such as applying only to specific out-of-hospital treatments.
What are health insurance waiting periods?
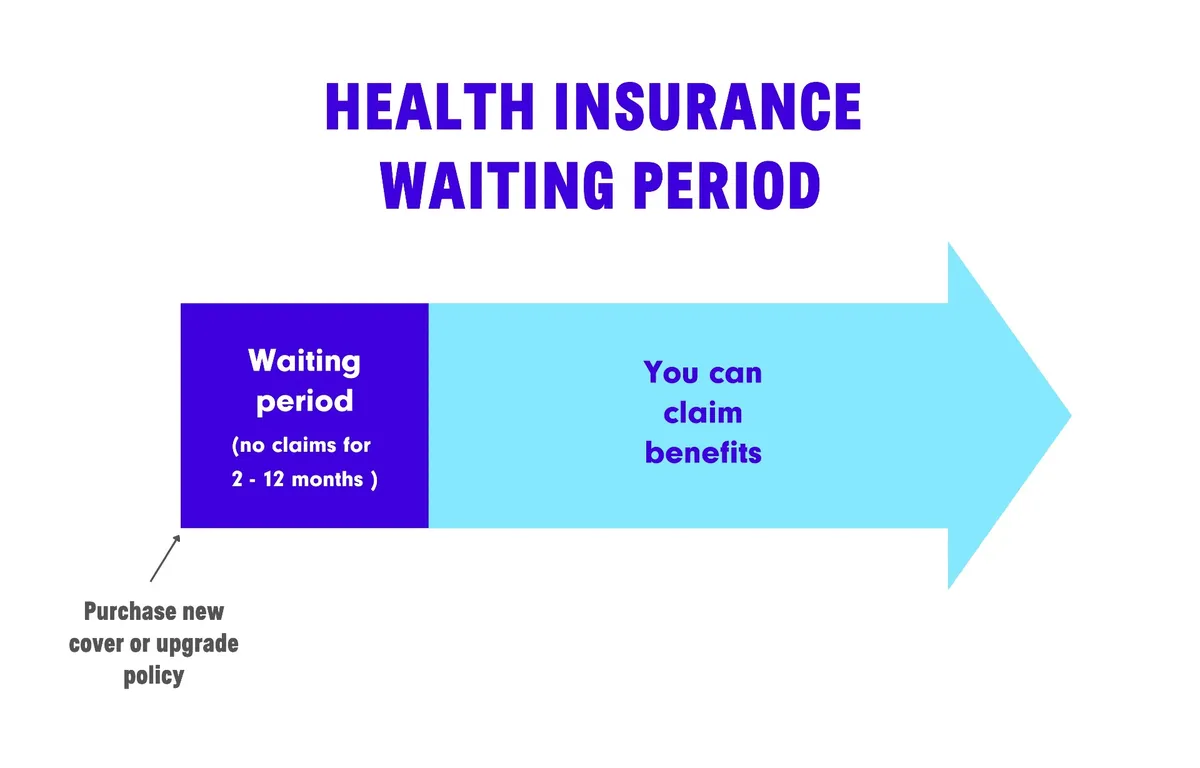
Health insurance waiting periods are the set timeframes you must wait after taking out a policy for the first time, or upgrading your cover, before you can claim benefits. Waiting periods apply to both Hospital and Extras cover.
The length of a waiting period depends on the type of treatment, usually ranging from two to 12 months.
For example, health insurance for pregnancy typically has a 12-month waiting period, so you would need to take out an appropriate level of hospital cover, such as Gold cover, and hold it for 12 months before you can claim for birth-related services and treatment.
Why do waiting periods apply?
According to PrivateHealth.gov.au, health insurance waiting periods help prevent people from taking out cover and making an immediate claim.
They protect existing members by reducing the risk of individuals making a large claim soon after joining and then cancelling their cover, which would otherwise lead to higher premiums for all policyholders.
Waiting periods are one of the potential disadvantages of health insurance, as they apply in most scenarios. But there are a handful of situations where getting health insurance with no waiting period may be possible. The catch is, you generally need to have cover in place already to qualify.
No waiting period health insurance on Extras cover
Here are some providers offering to waive the waiting periods on selected Extras.
Provider | AAMI |
|---|---|
No waiting period offer | AAMI is waiving the 2 & 6 month waiting periods on Extras for eligible new members that sign up for a combined Hospital and Extras product (T&Cs apply). |
Offer expires | 15 December 2026 |
Provider | ACA Health Benefits Fund |
No waiting period offer | Join now on combined Hospital and Extras and skip the 2 and 4 month wait on Extras (eligible new customers only, T&Cs apply). |
Offer expires | 30 November 2026 |
Provider | Apia Health |
No waiting period offer | Eligible new members joining on a combined Hospital and Extras cover can skip the 2 & 6 month waits on Extras. (T&Cs apply). |
Offer expires | 15 December 2026 |
Provider | Australian Seniors Health Insurance |
No waiting period offer | Astute is offering to waive 2, 3 & 6 month waiting periods on Extras for eligible new members who join an Astute Simplicity Health Insurance combined Hospital and Extras product through Astute's approved channels (T&Cs apply). |
Offer expires | 17 December 2026 |
Provider | Australian Unity |
No waiting period offer | Australian Unity is waiving 2 month waiting periods on Extras for eligible new members that sign up for a combined Hospital and Extras product (T&Cs apply). |
Offer expires | 30 November 2026 |
Provider | CBHS (restricted membership) |
No waiting period offer | CommBank employees and their families who take out a combined Hospital and Extras policy will have the 2 & 6 month waiting periods waived on Extras (eligible new customers only. T&Cs apply. |
Offer expires | 10 November 2026 |
Provider | HBF |
No waiting period offer | Join now on combined Hospital and Extras and skip the 2-month wait on Extras (eligible new customers only, T&Cs apply). |
Offer expires | 8 December 2026 |
Provider | HCF |
No waiting period offer | Join now on combined Hospital and Extras and skip the 2 month wait on Extras (eligible new customers only, T&Cs apply). |
Offer expires | 10 November 2026 |
Provider | ING Health Insurance |
No waiting period offer | ING will waive the 2 & 6 month waiting periods on Extras when you take out an eligible combined Hospital and Extras policy. T&Cs apply. |
Offer expires | 30 November 2026 |
Provider | Medibank |
No waiting period offer | Medibank offering to waive 2 & 6 month waiting periods on Extras when you join as a new customer on a combined hospital and extras policy. (T&Cs apply). |
Offer expires | Ongoing |
Provider | Navy Health (restricted membership) |
No waiting period offer | Join on combined Hospital and Extras cover to get the 2 & 6 month waiting periods waived on Extras (eligible ADF members and families only, T&Cs apply). |
Offer expires | 3 November 2026 |
Provider | nib |
No waiting period offer | Join now on combined Hospital and Extras and skip the 2 and 6 month wait on Extras (eligible new customers only, T&Cs apply). |
Offer expires | 30 November 2026 |
Provider | Queensland Country Health Fund |
No waiting period offer | Queensland Country Health Fund is offering to waive 2 month waiting periods on Extras when you join as a new customer on a combined hospital and extras policy. (T&Cs apply) |
Offer expires | 10 January 2027 |
Provider | Suncorp Bank |
No waiting period offer | Suncorp Bank is offering to waive 2 & 6 month waiting periods on Extras for eligible new members. T&Cs apply. |
Offer expires | 15 December 2026 |
| Provider | No waiting period offer | Offer expires |
|---|---|---|
AAMI | AAMI is waiving the 2 & 6 month waiting periods on Extras for eligible new members that sign up for a combined Hospital and Extras product (T&Cs apply). | 15 December 2026 |
ACA Health Benefits Fund | Join now on combined Hospital and Extras and skip the 2 and 4 month wait on Extras (eligible new customers only, T&Cs apply). | 30 November 2026 |
Apia Health | Eligible new members joining on a combined Hospital and Extras cover can skip the 2 & 6 month waits on Extras. (T&Cs apply). | 15 December 2026 |
Australian Seniors Health Insurance | Astute is offering to waive 2, 3 & 6 month waiting periods on Extras for eligible new members who join an Astute Simplicity Health Insurance combined Hospital and Extras product through Astute's approved channels (T&Cs apply). | 17 December 2026 |
Australian Unity | Australian Unity is waiving 2 month waiting periods on Extras for eligible new members that sign up for a combined Hospital and Extras product (T&Cs apply). | 30 November 2026 |
CBHS (restricted membership) | CommBank employees and their families who take out a combined Hospital and Extras policy will have the 2 & 6 month waiting periods waived on Extras (eligible new customers only. T&Cs apply. | 10 November 2026 |
HBF | Join now on combined Hospital and Extras and skip the 2-month wait on Extras (eligible new customers only, T&Cs apply). | 8 December 2026 |
HCF | Join now on combined Hospital and Extras and skip the 2 month wait on Extras (eligible new customers only, T&Cs apply). | 10 November 2026 |
ING Health Insurance | ING will waive the 2 & 6 month waiting periods on Extras when you take out an eligible combined Hospital and Extras policy. T&Cs apply. | 30 November 2026 |
Medibank | Medibank offering to waive 2 & 6 month waiting periods on Extras when you join as a new customer on a combined hospital and extras policy. (T&Cs apply). | Ongoing |
Navy Health (restricted membership) | Join on combined Hospital and Extras cover to get the 2 & 6 month waiting periods waived on Extras (eligible ADF members and families only, T&Cs apply). | 3 November 2026 |
nib | Join now on combined Hospital and Extras and skip the 2 and 6 month wait on Extras (eligible new customers only, T&Cs apply). | 30 November 2026 |
Queensland Country Health Fund | Queensland Country Health Fund is offering to waive 2 month waiting periods on Extras when you join as a new customer on a combined hospital and extras policy. (T&Cs apply) | 10 January 2027 |
Suncorp Bank | Suncorp Bank is offering to waive 2 & 6 month waiting periods on Extras for eligible new members. T&Cs apply. | 15 December 2026 |
How to get health insurance with no waiting period
Here are some situations when it may be possible to avoid health insurance waiting periods:
Switch to the same level cover or lower
You can get health insurance with no waiting period on a Hospital policy if you already have cover, and then sign up for a new policy that offers the same or a lower level of coverage.
The new insurer must recognise that you have already served the appropriate waiting period.
If your new policy includes coverage that your old policy didn’t, you may need to serve a waiting period for the new inclusions.
If you're switching from singles health insurance to a couples policy (or vice versa), the waiting period you already served as an individual would be recognised under the new policy.
Mental health exemption
If you have a Hospital policy that includes psychiatric cover, you may be able to upgrade to a higher level of psychiatric cover without needing to serve a further waiting period. You would need to already have served the two-month waiting period on your existing lower level of cover.
The ‘mental health waiting period exemption’ applies to mental health services and drug and alcohol treatment. You can only use this exemption once in your lifetime.
Note if you upgrade your cover in this way, your health insurance will likely become more expensive.
Extras cover with waiting periods waived
Waiting periods on Extras are not as strictly regulated. This means insurers have more flexibility to tailor waiting periods to particular conditions, or waive the waiting period entirely in some cases.
For example, it’s relatively common to see health insurance special offers where insurers offer Extras cover with no waiting period on certain conditions for new customers. This is usually a temporary special offer as opposed to a standard feature of the cover.
The waived waiting period is generally only for certain types of Extras cover – commonly those with a two- or six-month waiting period. The standard waiting period applies to anything else not included in the special offer.
Research from Money.com.au shows that the offer of waived waiting periods on Extras cover is the biggest motivation for around 15% of Australians when choosing a health insurance policy.
Waiting periods on hospital cover

Pregnancy and birth (12 months)
For pregnancy and birth-related services (obstetrics), you’ll need to serve a 12-month waiting period. This means if children are on the cards, you’ll need to take out an appropriate level of cover at least a year in advance of the due date if you want to claim maternity-related hospital services.

Pre-existing conditions (12 months)
The Private Health Insurance Ombudsman defines a pre-existing condition as any illness or ailment with signs or symptoms in the six months before you took out a hospital policy or upgraded your cover. These conditions come with a 12-month waiting period before you can make a claim.

Psychiatric care, rehabilitation and palliative care (2 months)
Psychiatric care, rehabilitation, and palliative care each have a two-month waiting period, even for pre-existing conditions. Psychiatric care involves hospital treatment for mental health; rehabilitation provides therapy and support after illness or surgery; and palliative care focuses on comfort and quality of life for people with serious illnesses.

In-hospital treatment (2 months)
A two-month waiting period applies to treatment in hospital for a range of conditions. This refers to both treatment as a private patient in a public or private hospital setting. Refer to the product disclosure statement (PDS) to see which waiting period applies to treatments covered under the hospital policy.
Waiting periods on extras cover
Unlike hospital cover, extras are not regulated in the same way, so waiting periods can vary between insurers and policies. This means health funds set their own waiting periods for extras. Here’s a typical guide for some common treatments:
- General dental (2 months): Most insurers require a two-month wait before you can claim for basic dental services like cleans, fillings and x-rays.
- Optical (2–6 months): Optical cover usually has a two-month waiting period, but some funds or policies may require up to six months.
- Physiotherapy (2–6 months): Waiting periods for physio, exercise programs and rehab for injuries or movement issues typically range from two to six months.
- Chiropractic & osteopathy (2 months): These services often have a two-month waiting period.
- Orthodontics & major dental (12 months): Major dental work and orthodontic treatments usually come with a 12-month waiting period.
- Podiatry (2–6 months): Treatments related to feet and ankles generally require a wait of two to six months.
- Ambulance (1 day): Emergency ambulance services commonly have a one-day waiting period.