

Is it better to get cashback or use points?
If you want a credit card that offers rewards based on your spending, whether you should choose cashback or rewards points is the million-dollar (or points) question.
Both cashback cards and traditional rewards cards allow you to earn a return on eligible spending with your credit card. Depending on which you choose, that return will come in the form of cash credited back to your account, or rewards points which you can use to pay for travel, gift cards and more.
Ultimately the goal is the same with both card types, but what they deliver for cardholders (and how) can vary significantly depending on the card you choose. Let’s take a look at how each card option works.
Credit card cashback vs rewards points: How they compare
Here's what’s typically on offer with cashback credit cards vs cards offering rewards points.
What you get | |
Cashback | Cold, hard cash – usually issued to you as a statement credit |
Points (rewards and frequent flyer) | Points issued through a rewards program and redeemable in a variety of ways |
Earn rates available | |
Cashback | Generally a fixed percentage of eligible spending, ranging from 0.5%–1% depending on the card |
Points (rewards and frequent flyer) | Varies by card but typically ranges from 0.5–2.5 points per $1 |
Earning limits | |
Cashback | Cashback is typically capped, either at a set amount per statement period or as a % of your credit limit |
Points (rewards and frequent flyer) | It’s common for rewards cards to limit the overall number of points you can earn per month or year |
What’s it worth? | |
Cashback | Cash is cash, so the value is easy to work out |
Points (rewards and frequent flyer) | The value of points varies depending on the rewards program issuing them and what they’re redeemed for |
Who sets the value? | |
Cashback | $1 of cashback will always be worth precisely $1 |
Points (rewards and frequent flyer) | The rewards program provider sets the value of points and can vary it at any time |
Eligible spending | |
Cashback | Most day-to-day spending is eligible for earning cashback |
Points (rewards and frequent flyer) | Most day-to-day spending is eligible for earning rewards points |
Common exclusions | |
Cashback | Cash advances, transfers, gambling, government payments, payments for card fees and interest or balance transfers |
Points (rewards and frequent flyer) | Cash advances, transfers, gambling, government payments, payments for card fees and interest or balance transfers |
Flexibility | |
Cashback | Cash is credited to your credit card account but generally can’t be transferred elsewhere |
Points (rewards and frequent flyer) | Can be converted to pretty much anything, including travel, gift cards and shopping |
Effort involved | |
Cashback | Very little – cashback accrues and is credited automatically |
Points (rewards and frequent flyer) | It depends – if you want to maximise the points you’re earning and the return you get from them, you’ll need to work for it, as earn and redemption rates vary significantly |
| Cashback | Points (rewards and frequent flyer) | |
|---|---|---|
What you get | Cold, hard cash – usually issued to you as a statement credit | Points issued through a rewards program and redeemable in a variety of ways |
Earn rates available | Generally a fixed percentage of eligible spending, ranging from 0.5%–1% depending on the card | Varies by card but typically ranges from 0.5–2.5 points per $1 |
Earning limits | Cashback is typically capped, either at a set amount per statement period or as a % of your credit limit | It’s common for rewards cards to limit the overall number of points you can earn per month or year |
What’s it worth? | Cash is cash, so the value is easy to work out | The value of points varies depending on the rewards program issuing them and what they’re redeemed for |
Who sets the value? | $1 of cashback will always be worth precisely $1 | The rewards program provider sets the value of points and can vary it at any time |
Eligible spending | Most day-to-day spending is eligible for earning cashback | Most day-to-day spending is eligible for earning rewards points |
Common exclusions | Cash advances, transfers, gambling, government payments, payments for card fees and interest or balance transfers | Cash advances, transfers, gambling, government payments, payments for card fees and interest or balance transfers |
Flexibility | Cash is credited to your credit card account but generally can’t be transferred elsewhere | Can be converted to pretty much anything, including travel, gift cards and shopping |
Effort involved | Very little – cashback accrues and is credited automatically | It depends – if you want to maximise the points you’re earning and the return you get from them, you’ll need to work for it, as earn and redemption rates vary significantly |
Pros and cons of cashback vs rewards points
What’s good about cashback?
- It’s simple and transparent: The earn mechanism is usually straightforward as a percentage of eligible spending.
- The value is fixed: $1 earned in cashback will always equal $1.
- You’ll definitely use it: Beyond some diabolical outcome for humanity, cash doesn’t expire! Cashback on your credit card simply offsets your ongoing spending.

What’s less good about cashback?
- Limited options currently: There are only a handful of credit cards on Money.com.au’s database offering ongoing cashback based on spending. Cards offering points are far more common.
- Limits & exclusions apply: You won’t earn cashback on every single $1 you spend. Your spending on purchases in-store and online is typically included as standard, but some less common transactions (like money transfers) don’t qualify. Total cashback earnings are usually also capped.

What’s good about rewards points?
- Lots of choice: There are dozens of credit cards on our database offering rewards points and a wide range of rewards programs to choose from.
- They’re flexible: You can convert credit card points into pretty much anything.
- There's a high ceiling: On premium (more expensive) cards, there’s scope to earn a lot of points if you’re a big spender. If you use your points well, the conversion rates can be generous too (e.g. paying for flights often offers a particularly good return).
What’s less good about rewards points?
- The value is often unclear: Rewards points can get extremely complicated. Earn rates and redemption rates can vary massively from card to card and program to program. The value of points can be changed by the provider at any time.
- Limits & exclusions apply: You’re unlikely to earn rewards on every single $1 you spend. Some transactions don’t qualify and total points earning is often capped.
- There’s work involved: To get any value from your points, you typically need to actively convert them into something you want (some programs offer auto-redemption). You’ll also be at the mercy of how easy or difficult your specific rewards program’s redemption options are to compare and use. The customer experience is far from uniform.
Are rewards cards or cashback cards more expensive?
Rewards points cards are generally more expensive, with an average ongoing annual card fee of $262, versus $99 on average for cashback cards. That’s according to Money.com.au’s analysis of more than 100 rewards credit cards and eight credit cards offering cashback as an ongoing basis from our database (excluding intro annual fee offers), as at October 2026.
Looking at the median gives a better sense of a ‘typical’ card in each category. This works out as $175 a year for a rewards card versus $89 for a cashback card.
But bear in mind that the annual fee on a credit card reflects the overall benefits of the card, not just points or cashback. When choosing a card, it’s worth looking at the full package.
For example, frequent flyer points cards often include extras like complimentary travel insurance, airport lounge access and travel credits.
Cashback cards, on the other hand, tend not to offer those specific benefits usually associated with the most expensive cards, but often still come with useful extras like purchase protection insurance and mobile phone insurance.
Cashback vs points: a worked example
How do cashback and points cards compare in practice? We put a typical cashback card up against a typical points card, based on the average spending per Australian credit card account of $3,284 a month. We’ve also included the MONEYME Cashback Rewards Credit Card, one of the highest-earning cashback cards in our database. Both cashback options come out well ahead of the typical points card.
Return per eligible $1 spent | |
Typical cashback card | 0.67c |
Typical points card | 0.54c (when converted to gift cards) |
MONEYME Cashback Rewards Credit Card | 1.00c |
Rewards earned in a year | |
Typical cashback card | $264 |
Typical points card | $213 |
MONEYME Cashback Rewards Credit Card | $394 |
Annual fee | |
Typical cashback card | $89 |
Typical points card | $175 |
MONEYME Cashback Rewards Credit Card | $149 ($0 in the first year) |
Net value | |
Typical cashback card | $175 |
Typical points card | $38 |
MONEYME Cashback Rewards Credit Card | $245 ($394 in the first year) |
| Typical cashback card | Typical points card | MONEYME Cashback Rewards Credit Card | |
|---|---|---|---|
Return per eligible $1 spent | 0.67c | 0.54c (when converted to gift cards) | 1.00c |
Rewards earned in a year | $264 | $213 | $394 |
Annual fee | $89 | $175 | $149 ($0 in the first year) |
Net value | $175 | $38 | $245 ($394 in the first year) |
Is cashback 'having a moment' in 2026?
Sean Callery, Editor of Money.com.au
"Recent RBA card payment reforms have resulted in some rewards card programs cutting back on rewards earn rates and redemption rates. Fees and interest rates on some cards have also gone up. Overall, it increases the relative appeal of cashback as a simpler reward with a more predictable value.
Even before these changes, a February 2026 YouGov survey of 1,020 Australian credit card holders, commissioned by MONEYME, found 69% felt points didn’t always suit their lifestyle, 58% found them harder to redeem than they should be, and 37% struggled to understand their value. Meanwhile, 85% said they would consider switching to cashback."
Sean Callery, Editor of Money.com.au
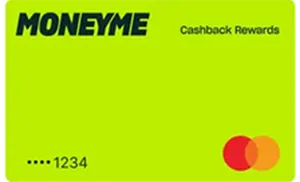
Featured card: MONEYME Cashback Rewards Credit Card*
MONEYME’s Cashback Rewards Credit Card currently offers the highest cashback earn rate among the products on Money.com.au’s credit card database.
It offers 1% cashback on almost everything you buy. The earning mechanism is simple too, with no complicated tiers. It’s just money back every time you tap your card or shop online.
For a limited time, you’ll pay a $0 annual fee in your first year when you sign up before 15 November 2026.
You also get:
- Access to your card in as little as 60 minutes from application.
- Up to 44 interest-free days on purchases
- Purchase Protection Insurance
- Mobile Phone Protection Insurance (when you pay your phone bill with the card)
- Event Ticket Protection, which helps if you miss a ticketed event you booked with the card.

MONEYME Cashback Rewards Credit Card – detailed breakdown
Cashback
1%
on eligible purchases
Annual fee
$0
in year one, then $149 p.a.
Interest rate
19.99% to 26.99%
p.a.
Purchase protection insurance
Yes
Plus mobile insurance and ticket cover
Money's take
The MONEYME Cashback Rewards Credit Card has no annual fee in the first year (offer ends 15 November 2026; $149 a year thereafter). It also offers 1% back on eligible purchases. That’s actually a pret...

Pros
- Earn cashback on eligible spending
- No annual fee in year one (sign up before 15 Nov 2026)
- Up to 44 days interest free
- Low minimum credit limit
- Purchase protection insurance

Cons
- High interest rate on purchases
- Expensive for cash advances
- High foreign exchange fees

Additional information
- Card Type: Mastercard