Is it worth refinancing when your home loan is going to change hands?
If you've recently learned that your home loan is going to be transferred to a new lender, now is a good time to review your situation and make a deliberate decision about which lender you want to be with.
You can’t opt out of the transfer. It's happening whether you like it or not, but taking a look at your options, and refinancing if it makes sense, puts you back in the driver's seat.
In some cases, the actual changes to your loan as part of a lender transfer may be minimal. But across our brokers’ recent conversations with Suncorp and HSBC customers, there were compelling reasons for some borrowers to switch before the move.

1. Your rate isn't competitive
If you're rate isn't competitive now, it's unlikely to improve with the lender you'll be transferred to. Several customers we spoke to in this position didn't know their rate until they checked. Those who refinanced got rates around 25 to 35 basis points lower.

2. You'll lose a feature you use
ANZ allows one offset account per home loan, so Suncorp borrowers who currently have multiple offset accounts will need a change of plan.

3. Your minimum repayment will increase
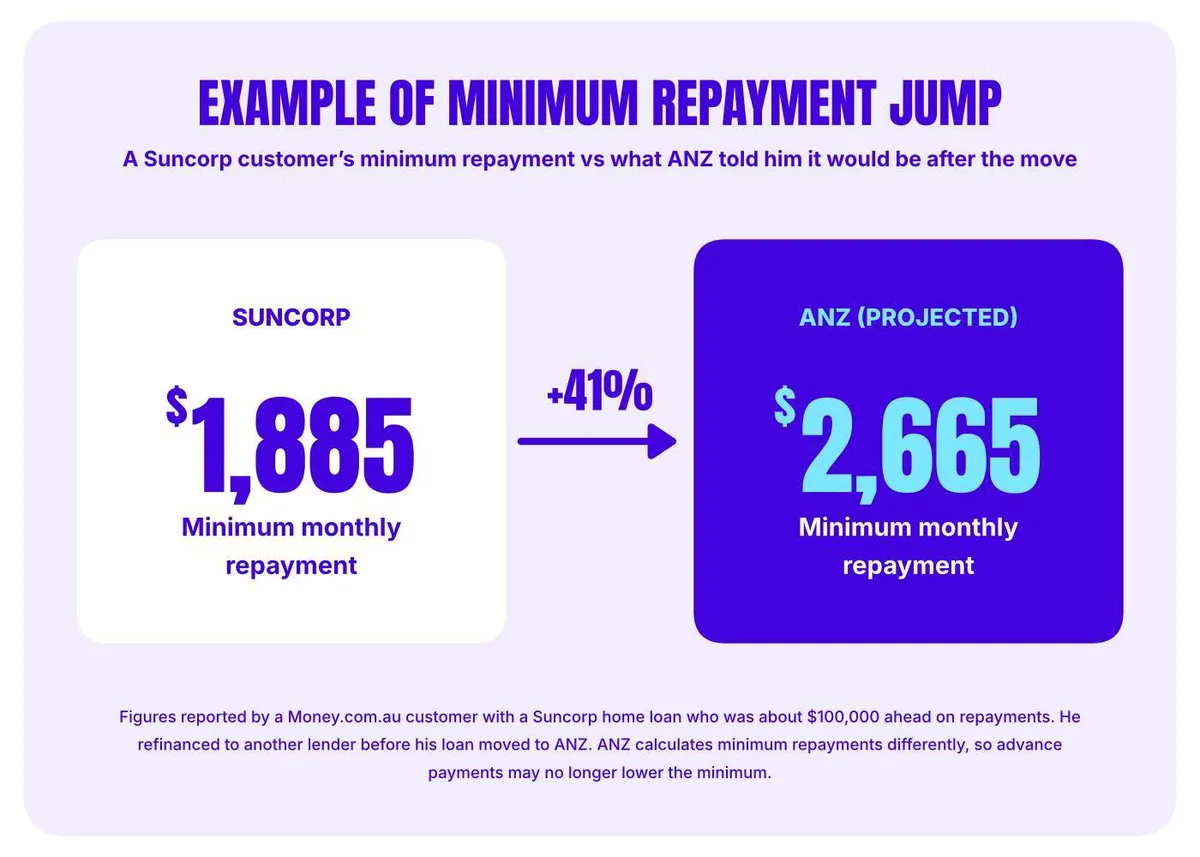
Suncorp borrowers who've made advance payments are likely to face a higher minimum repayment at ANZ. One of our clients was told his would rise from $1,885 to $2,665 a month.

4. Your everyday banking has to move anyway
As a non-bank lender, Pepper Money doesn't offer transaction or savings accounts. Some HSBC home loan customers who also have their everyday banking there are interested in finding a new provider that can do everything under one roof.
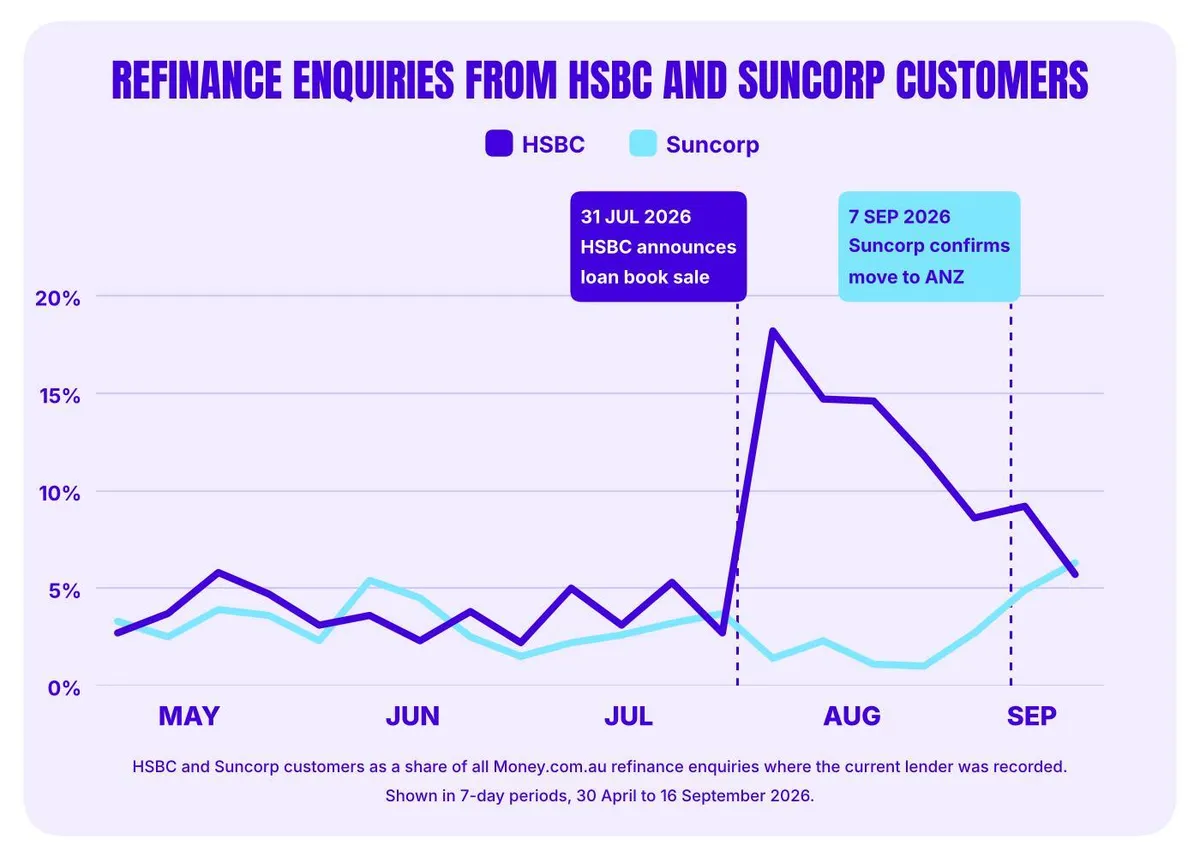
We've seem a spike in refinance enquiries from HSBC and Suncorp customers
Money.com.au borrower data shows that HSBC customers made up about 4% of refinance enquiries from April to July 2026, but that rose to almost 14% of the total in the month of August this year. Early September data suggests a similar trend is emerging among Suncorp customers.
When staying put might be better
These were the situations where staying put was the better call for clients we spoke to.
- You’re already on a good rate, which carries over unchanged.
- You’re on a fixed rate and ending it early would trigger break costs. Wait until the fixed term ends and reassess then.
- The loan features you use aren't changing.
- What you would have saved with a marginally lower rate wouldn't have covered the cost of switching. Among customers we dealt with in this situation, refinancing typically cost about $700 to $1,050 per property.

To see what's changing for your loan, check your lender's own information: Suncorp's Move Hub or Pepper Money's HSBC page.
How to decide whether to stay or refinance
This is the actual process our brokers run through with customers who are not sure whether to stick or twist when they’ve been notified their loan is moving to a new lender:
Check what's changing for your loan.
Read the letter or email from your lender. If you're with Suncorp, run the repayment calculator to see your new minimum.
Find your current rate and repayment.
Several customers we spoke to didn't know theirs. Check your app or latest statement. If you're on a fixed rate, ask your lender what you'll revert to.
List the features you actually use.
Every customer in our broker calls named one they wanted to keep, from fee-free redraw to multiple offset accounts.
Get a real quote.
A broker can ask lenders to price your loan, and several customers we spoke to were offered rates below the advertised rate.
Compare the savings with the cost.
If the saving clearly beats the cost of switching, or you'd keep a feature you'd otherwise lose, refinancing is worth it.
How to refinance when your loan is being transferred
The refinance process itself is the same as any other, and our refinance guide covers it step by step. A few things are different when your lender is changing.
- Start early: A refinance typically takes two to five weeks. Suncorp says it will stop processing some requests closer to its move date, so don't leave it until the last few weeks.
- Expect a discharge fee: A lot of customers are asking why they should have to pay to leave when they didn't choose the change, and it’s a very fair question. Unfortunately, lenders generally still charge it and from what we are seeing with clients, that is the case with both HSBC ($395) and Suncorp ($350).
- Keep your buffer if you're ahead: Refinancing pays out your balance only, so money you've paid in advance doesn't come with you. If you want that cushion in your new loan's redraw, consider refinancing to a higher amount. A number of customers we’ve worked with did exactly this.

How two of our customers arrived at different decisions on whether to switch
1. Stayed put as their rate was competitive
A Queensland couple with a HSBC loan wanted to leave before the transfer, worried about future rate rises. But their HSBC rate was already competitive.
With HSBC rates carrying over unchanged when the transfer happens, our recommendation was to sit tight. Staying and checking the rate against the market afterwards is a reasonable choice for borrowers like them.
2. Refinancing because of the repayment change
A NSW borrower with a Suncorp loan had paid about $100,000 ahead of schedule. ANZ told him his minimum repayment would rise from $1,885 to $2,665 a month after the move. He could afford it, but he valued the low minimum as a safety net.
He refinanced to a basic loan with redraw at a rate about 26 basis points lower than his Suncorp rate. He borrowed slightly more than his balance to keep a buffer in redraw, and kept his remaining loan term rather than resetting to 30 years.
Recent history of lender closures and mergers in Australia
Year | 2027 (pending) |
|---|---|
Lender(s) | HSBC |
What happened | Australian home and personal loan portfolio to be sold to Blackstone, with Pepper Money managing and servicing the loans. Completion expected in the first half of 2027, subject to regulatory approval. |
Year | 2027 (pending) |
Lender(s) | Suncorp Bank |
What happened | Customers to move to ANZ products and platforms by June 2027, bringing both banks under the ANZ brand following the 2024 acquisition. |
Year | 2026 |
Lender(s) | Australian Mutual Bank |
What happened | Merged with Teachers Mutual Bank Limited, retaining its brand. |
Year | 2026 |
Lender(s) | RAMS |
What happened | A consortium including Pepper Money acquired Westpac’s RAMS home loan portfolio. |
Year | 2025 |
Lender(s) | Australian Unity Bank |
What happened | Transferred its banking business to Bank Australia. |
Year | 2025 |
Lender(s) | Qudos Bank |
What happened | Merged with Bank Australia, initially retaining both brands. |
Year | 2025 |
Lender(s) | Auswide Bank |
What happened | Merged with MyState, initially retaining both brands. |
Year | 2024 |
Lender(s) | Suncorp Bank |
What happened | Acquired by ANZ. |
Year | 2023 |
Lender(s) | Greater Bank and Newcastle Permanent |
What happened | Merged to form Newcastle Greater Mutual Group, retaining both brands. |
Year | 2023 |
Lender(s) | Heritage Bank and People’s Choice |
What happened | Merged to form the organisation subsequently branded People First Bank. |
Year | 2022 |
Lender(s) | Citi’s Australian consumer banking business |
What happened | Acquired by NAB, including its home loans. |
Year | 2021 |
Lender(s) | ME Bank |
What happened | Acquired by Bank of Queensland (BOQ). |
Year | 2021 |
Lender(s) | 86 400 |
What happened | Acquired by NAB and subsequently integrated into ubank. |
Year | 2020 |
Lender(s) | Hunter United Credit Union |
What happened | Merged with IMB Bank. |
Year | 2019 |
Lender(s) | BCU |
What happened | Merged with P&N Bank, retaining both brands. |
Year | 2019 |
Lender(s) | Sydney Mutual Bank and Endeavour Mutual Bank |
What happened | Merged to form the organisation now known as Australian Mutual Bank. |
Year | 2016 |
Lender(s) | QT Mutual Bank |
What happened | Merged with RACQ, subsequently becoming RACQ Bank. |
Year | 2016 |
Lender(s) | Homeloans Ltd and RESIMAC |
What happened | Merged, subsequently adopting the Resimac name. |
Year | 2016 |
Lender(s) | Fire Brigades Employees Credit Union |
What happened | Merged with Teachers Mutual Bank, becoming Firefighters Mutual Bank. |
Year | 2016 |
Lender(s) | Sutherland Credit Union |
What happened | Merged with IMB Bank. |
Year | 2016 |
Lender(s) | Your Credit Union |
What happened | Acquired by Auswide Bank. |
Year | 2015 |
Lender(s) | UniCredit |
What happened | Merged with Teachers Mutual Bank, becoming UniBank. |
Year | 2014 |
Lender(s) | Investec’s Australian professional finance business |
What happened | Acquired by BOQ and rebranded BOQ Specialist. |
Year | 2014 |
Lender(s) | State Custodians |
What happened | Became wholly owned by Resimac, following its majority investment in 2011. |
Year | 2013 |
Lender(s) | Virgin Money Australia |
What happened | Acquired by BOQ. |
Year | 2012 |
Lender(s) | Bank of Cyprus Australia |
What happened | Acquired by Bendigo and Adelaide Bank, subsequently becoming Delphi Bank. |
Year | 2011 |
Lender(s) | The Rock Building Society |
What happened | Acquired by MyState. |
Year | 2008 |
Lender(s) | Bankwest |
What happened | Acquired by Commonwealth Bank. |
Year | 2008 |
Lender(s) | St.George Bank |
What happened | Merged with Westpac, bringing BankSA into Westpac Group. |
Year | 2008 |
Lender(s) | RAMS |
What happened | Westpac acquired the RAMS brand and distribution business, excluding its original mortgage book. |
Year | 2008 |
Lender(s) | Mackay Permanent Building Society |
What happened | Acquired by Wide Bay Australia, subsequently renamed Auswide Bank. |
Year | 2007 |
Lender(s) | Adelaide Bank |
What happened | Merged with Bendigo Bank. |
Year | 2007 |
Lender(s) | Home Building Society |
What happened | Acquired by BOQ. |
Year | 2006 |
Lender(s) | Pioneer Permanent Building Society |
What happened | Acquired by BOQ. |
| Year | Lender(s) | What happened |
|---|---|---|
2027 (pending) | HSBC | Australian home and personal loan portfolio to be sold to Blackstone, with Pepper Money managing and servicing the loans. Completion expected in the first half of 2027, subject to regulatory approval. |
2027 (pending) | Suncorp Bank | Customers to move to ANZ products and platforms by June 2027, bringing both banks under the ANZ brand following the 2024 acquisition. |
2026 | Australian Mutual Bank | Merged with Teachers Mutual Bank Limited, retaining its brand. |
2026 | RAMS | A consortium including Pepper Money acquired Westpac’s RAMS home loan portfolio. |
2025 | Australian Unity Bank | Transferred its banking business to Bank Australia. |
2025 | Qudos Bank | Merged with Bank Australia, initially retaining both brands. |
2025 | Auswide Bank | Merged with MyState, initially retaining both brands. |
2024 | Suncorp Bank | Acquired by ANZ. |
2023 | Greater Bank and Newcastle Permanent | Merged to form Newcastle Greater Mutual Group, retaining both brands. |
2023 | Heritage Bank and People’s Choice | Merged to form the organisation subsequently branded People First Bank. |
2022 | Citi’s Australian consumer banking business | Acquired by NAB, including its home loans. |
2021 | ME Bank | Acquired by Bank of Queensland (BOQ). |
2021 | 86 400 | Acquired by NAB and subsequently integrated into ubank. |
2020 | Hunter United Credit Union | Merged with IMB Bank. |
2019 | BCU | Merged with P&N Bank, retaining both brands. |
2019 | Sydney Mutual Bank and Endeavour Mutual Bank | Merged to form the organisation now known as Australian Mutual Bank. |
2016 | QT Mutual Bank | Merged with RACQ, subsequently becoming RACQ Bank. |
2016 | Homeloans Ltd and RESIMAC | Merged, subsequently adopting the Resimac name. |
2016 | Fire Brigades Employees Credit Union | Merged with Teachers Mutual Bank, becoming Firefighters Mutual Bank. |
2016 | Sutherland Credit Union | Merged with IMB Bank. |
2016 | Your Credit Union | Acquired by Auswide Bank. |
2015 | UniCredit | Merged with Teachers Mutual Bank, becoming UniBank. |
2014 | Investec’s Australian professional finance business | Acquired by BOQ and rebranded BOQ Specialist. |
2014 | State Custodians | Became wholly owned by Resimac, following its majority investment in 2011. |
2013 | Virgin Money Australia | Acquired by BOQ. |
2012 | Bank of Cyprus Australia | Acquired by Bendigo and Adelaide Bank, subsequently becoming Delphi Bank. |
2011 | The Rock Building Society | Acquired by MyState. |
2008 | Bankwest | Acquired by Commonwealth Bank. |
2008 | St.George Bank | Merged with Westpac, bringing BankSA into Westpac Group. |
2008 | RAMS | Westpac acquired the RAMS brand and distribution business, excluding its original mortgage book. |
2008 | Mackay Permanent Building Society | Acquired by Wide Bay Australia, subsequently renamed Auswide Bank. |
2007 | Adelaide Bank | Merged with Bendigo Bank. |
2007 | Home Building Society | Acquired by BOQ. |
2006 | Pioneer Permanent Building Society | Acquired by BOQ. |