Money

Top credit cards for earning rewards points on ATO payments

  • You can still use your credit card to make ATO payments until 30 June 2027, with no card surcharge.

  • See the top personal and business credit cards on our database for earning points on government and tax payments.

Isabella Visser Profile Photo
Sean Callery Editor Money.com.au

Rewards credit card guide written by Isabella Visser and fact checked by Sean Callery.

Sponsored

Our Top Offer For

Rewards

American Express Platinum Business Card

American Express® Platinum Business Card

Earn 350,000 bonus Membership Rewards® Points + an $875 Credit.

View Terms

Our Top Offer For

Rewards

American Express® Business Gold Plus Card

American Express® Business Gold Plus Card

Earn 250,000 Bonus Membership Rewards® Points.

View Terms

Our Top Offer For

Frequent Flyer

American Express Qantas Business Rewards Card

American Express® Qantas Business Rewards Card

Earn 150,000 bonus Qantas Points + $200 in your Qantas Business Rewards Travel Fund.

View Terms

Our Top Offer For

Frequent Flyer

American Express Velocity Business Card

The American Express® Velocity Business Card

Earn 200,000 bonus Velocity Points.

View Terms

Credit cards with the top points earn rates on ATO spending

For a limited time, a series of regulatory changes and bureaucratic backflips have created a window of opportunity for taxpayers (individual and business) to potentially earn credit card points on spending with the ATO, with no card surcharge.

The trouble is a lot of rewards credit cards don't let you earn points of spending with the government. But some do. Below we list the top cards on our database for earning points on your tax bill, and read on for further context on the timeline for using your card with the ATO and what you need to watch out for before you choose a card.

What kind of card are you looking for?

Top personal credit cards for earning rewards points on ATO spend

American Express Platinum Edge credit card

Points per $1 on ATO payments

1 Membership Rewards Point

How many points you’d earn on a $10,000 tax bill

10,000 Membership Rewards Points

Indicative points value (gift cards)

$50

Annual fee

$0 annual fee in first year (then $195 thereafter)

Purchase rate

23.99% p.a.

American Express Explorer Credit card

Points per $1 on ATO payments

1 Membership Rewards Point

How many points you’d earn on a $10,000 tax bill

10,000 Membership Rewards Points

Indicative points value (gift cards)

$50

Annual fee

$395

Purchase rate

23.99% p.a.

American Express Platinum Card

Points per $1 on ATO payments

1 Membership Rewards Point

How many points you’d earn on a $10,000 tax bill

10,000 Membership Rewards Points

Indicative points value (gift cards)

$50

Annual fee

$1,450

Purchase rate

n/a

American Express Velocity Escape Plus Card

Points per $1 on ATO payments

0.5 Velocity Points

How many points you’d earn on a $10,000 tax bill

5,000 Velocity Points

Indicative points value (gift cards)

$25.75

Annual fee

$95

Purchase rate

23.99% p.a.

American Express Velocity Platinum Card

Points per $1 on ATO payments

0.5 Velocity Points

How many points you’d earn on a $10,000 tax bill

0.5 Velocity Points

Indicative points value (gift cards)

$25.75

Annual fee

$440

Purchase rate

23.99% p.a.

American Express Qantas Discovery card

Points per $1 on ATO payments

0.5 Qantas Points

How many points you’d earn on a $10,000 tax bill

5,000 Qantas Points

Indicative points value (gift cards)

$21

Annual fee

$0

Purchase rate

23.99% p.a.

American Express Qantas Premium Card

Points per $1 on ATO payments

0.5 Qantas Points

How many points you’d earn on a $10,000 tax bill

5,000 Qantas Points

Indicative points value (gift cards)

$21

Annual fee

$249

Purchase rate

23.99% p.a.

American Express Qantas Ultimate Card

Points per $1 on ATO payments

0.5 Qantas Points

How many points you’d earn on a $10,000 tax bill

5,000 Qantas Points

Indicative points value (gift cards)

$21

Annual fee

$450

Purchase rate

23.99% p.a.

Points per $1 on ATO payments How many points you’d earn on a $10,000 tax billIndicative points value (gift cards)Annual fee Purchase rate

American Express Platinum Edge credit card

1 Membership Rewards Point

10,000 Membership Rewards Points

$50

$0 annual fee in first year (then $195 thereafter)

23.99% p.a.

American Express Explorer Credit card

1 Membership Rewards Point

10,000 Membership Rewards Points

$50

$395

23.99% p.a.

American Express Platinum Card

1 Membership Rewards Point

10,000 Membership Rewards Points

$50

$1,450

n/a

American Express Velocity Escape Plus Card

0.5 Velocity Points

5,000 Velocity Points

$25.75

$95

23.99% p.a.

American Express Velocity Platinum Card

0.5 Velocity Points

0.5 Velocity Points

$25.75

$440

23.99% p.a.

American Express Qantas Discovery card

0.5 Qantas Points

5,000 Qantas Points

$21

$0

23.99% p.a.

American Express Qantas Premium Card

0.5 Qantas Points

5,000 Qantas Points

$21

$249

23.99% p.a.

American Express Qantas Ultimate Card

0.5 Qantas Points

5,000 Qantas Points

$21

$450

23.99% p.a.

Card info per Money.com.au’s credit card database as at 21 October 2026 and subject to change. Points value estimate based on published conversion examples sourced from each provider’s website. Conversion value may vary depending on what points are redeemed for. The table is sorted from highest to lowest indicative value of points earned in the example scenario.

Top business credit cards for earning rewards points on ATO spend

NAB Rewards Business Signature Card

Points per $1 on ATO payments

1.25 NAB Rewards Points (excluding BPAY payments)

Points you'd earn on $50,000 ATO spend

62,500 NAB Rewards Points

Indicative points value (gift cards)

$306.25

Annual fee

$175

Purchase rate

19.50% p.a.

American Express Business Gold Plus Card

Points per $1 on ATO payments

1 Membership Rewards Point

Points you'd earn on $50,000 ATO spend

50,000 Membership Rewards Points

Indicative points value (gift cards)

$250

Annual fee

$395

Purchase rate

n/a

American Express Platinum Business card

Points per $1 on ATO payments

1 Membership Rewards Point

Points you'd earn on $50,000 ATO spend

50,000 Membership Rewards Points

Indicative points value (gift cards)

$250

Annual fee

$1,750

Purchase rate

n/a

CommBank Business Platinum Credit Card

Points per $1 on ATO payments

1–1.5 CommBank Yello points, depending on Yello tier

Points you'd earn on $50,000 ATO spend

50,000–75,000 points

Indicative points value (gift cards)

$200–$300

Annual fee

$300

Purchase rate

20.74% p.a.

Bank of Melbourne Amplify Business Credit Card

Points per $1 on ATO payments

1 Amplify Point

Points you'd earn on $50,000 ATO spend

50,000 Amplify Points

Indicative points value (gift cards)

$170

Annual fee

$0 annual fee in first year (then $89 thereafter)

Purchase rate

19.49% p.a.

St.George Amplify Business credit card

Points per $1 on ATO payments

1 Amplify Point

Points you'd earn on $50,000 ATO spend

50,000 Amplify Points

Indicative points value (gift cards)

$170

Annual fee

$0 annual fee in first year (then $89 thereafter)

Purchase rate

19.49% p.a.

BankSA Amplify Business Credit card

Points per $1 on ATO payments

1 Amplify Point

Points you'd earn on $50,000 ATO spend

50,000 Amplify Points

Indicative points value (gift cards)

$170

Annual fee

$0 annual fee in first year (then $89 thereafter)$0

Purchase rate

19.49% p.a.

Westpac Altitude Business Platinum Mastercard

Points per $1 on ATO payments

1 Altitude Point

Points you'd earn on $50,000 ATO spend

50,000 Altitude Points

Indicative points value (gift cards)

$170

Annual fee

$0 annual fee in first year (then $200 thereafter)

Purchase rate

20.74% p.a.

ANZ Business Black Credit card

Points per $1 on ATO payments

0.5 Rewards Points

Points you'd earn on $50,000 ATO spend

25,000 Rewards Points

Indicative points value (gift cards)

$111.11

Annual fee

$300

Purchase rate

20.24% p.a.

Westpac Altitude Business Gold Mastercard

Points per $1 on ATO payments

0.5 Altitude Business Reward Points (capped at 20,000 per statement period)

Points you'd earn on $50,000 ATO spend

20,000 Altitude Business Reward Points

Indicative points value (gift cards)

$68

Annual fee

$0 annual fee in first year (then $150 thereafter)

Purchase rate

20.24% p.a.

Points per $1 on ATO payments Points you'd earn on $50,000 ATO spendIndicative points value (gift cards)Annual fee Purchase rate

NAB Rewards Business Signature Card

1.25 NAB Rewards Points (excluding BPAY payments)

62,500 NAB Rewards Points

$306.25

$175

19.50% p.a.

American Express Business Gold Plus Card

1 Membership Rewards Point

50,000 Membership Rewards Points

$250

$395

n/a

American Express Platinum Business card

1 Membership Rewards Point

50,000 Membership Rewards Points

$250

$1,750

n/a

CommBank Business Platinum Credit Card

1–1.5 CommBank Yello points, depending on Yello tier

50,000–75,000 points

$200–$300

$300

20.74% p.a.

Bank of Melbourne Amplify Business Credit Card

1 Amplify Point

50,000 Amplify Points

$170

$0 annual fee in first year (then $89 thereafter)

19.49% p.a.

St.George Amplify Business credit card

1 Amplify Point

50,000 Amplify Points

$170

$0 annual fee in first year (then $89 thereafter)

19.49% p.a.

BankSA Amplify Business Credit card

1 Amplify Point

50,000 Amplify Points

$170

$0 annual fee in first year (then $89 thereafter)$0

19.49% p.a.

Westpac Altitude Business Platinum Mastercard

1 Altitude Point

50,000 Altitude Points

$170

$0 annual fee in first year (then $200 thereafter)

20.74% p.a.

ANZ Business Black Credit card

0.5 Rewards Points

25,000 Rewards Points

$111.11

$300

20.24% p.a.

Westpac Altitude Business Gold Mastercard

0.5 Altitude Business Reward Points (capped at 20,000 per statement period)

20,000 Altitude Business Reward Points

$68

$0 annual fee in first year (then $150 thereafter)

20.24% p.a.

Card info per Money.com.au’s credit card database as at 21 October 2026 and subject to change. Points value estimate based on published conversion examples sourced from each provider’s website. Conversion value may vary depending on what points are redeemed for. The table is sorted from highest to lowest indicative value of points earned in the example scenario.

Top business frequent flyer cards for earning rewards points on ATO spend

Credit card

American Express Qantas Business Rewards Card

Points per $1 on ATO payments

0.5 Qantas Points

Points you’d earn on a $50,000 tax bill

25,000 Qantas Points

Annual fee

$450

Purchase rate

n/a

Credit card

American Express Velocity Business Card

Points per $1 on ATO payments

0.5 Velocity Points

Points you’d earn on a $50,000 tax bill

25,000 Velocity Points

Annual fee

$249

Purchase rate

n/a

Credit card

ANZ Qantas Business Rewards Credit Card

Points per $1 on ATO payments

0.5 Qantas Points

Points you’d earn on a $50,000 tax bill

25,000 Qantas Points

Annual fee

$300

Purchase rate

20.24% p.a.

Credit card

Westpac Business Choice Rewards Platinum Mastercard

Points per $1 on ATO payments

0.333 up to a maximum of 100,000 Qantas Points per facility per month

Points you’d earn on a $50,000 tax bill

16,667 Qantas Points

Annual fee

$150

Purchase rate

20.24% p.a.

Credit card

Bendigo Bank Qantas Business Credit card

Points per $1 on ATO payments

0.3 Qantas Points

Points you’d earn on a $50,000 tax bill

15,000 Qantas Points

Annual fee

$89

Purchase rate

19.99% p.a.

Credit card

BankSA Amplify Business Credit Card - Qantas Points

Points per $1 on ATO payments

0.25 Qantas Points

Points you’d earn on a $50,000 tax bill

12,500 Qantas Points

Annual fee

$0 annual fee in first year (then $89 thereafter)

Purchase rate

19.49% p.a.

Credit card

St.George Amplify Business Credit Card - Qantas points

Points per $1 on ATO payments

0.25 Qantas Points

Points you’d earn on a $50,000 tax bill

12,500 Qantas Points

Annual fee

$0 annual fee in first year (then $89 thereafter)

Purchase rate

19.49% p.a.

Credit card

Bank of Melbourne Amplify Business Credit Card

Points per $1 on ATO payments

0.25 Qantas Points

Points you’d earn on a $50,000 tax bill

12,500 Qantas Points

Annual fee

$0 annual fee in first year (then $89 thereafter)

Purchase rate

19.49% p.a.

Credit card Points per $1 on ATO payments Points you’d earn on a $50,000 tax billAnnual fee Purchase rate

American Express Qantas Business Rewards Card

0.5 Qantas Points

25,000 Qantas Points

$450

n/a

American Express Velocity Business Card

0.5 Velocity Points

25,000 Velocity Points

$249

n/a

ANZ Qantas Business Rewards Credit Card

0.5 Qantas Points

25,000 Qantas Points

$300

20.24% p.a.

Westpac Business Choice Rewards Platinum Mastercard

0.333 up to a maximum of 100,000 Qantas Points per facility per month

16,667 Qantas Points

$150

20.24% p.a.

Bendigo Bank Qantas Business Credit card

0.3 Qantas Points

15,000 Qantas Points

$89

19.99% p.a.

BankSA Amplify Business Credit Card - Qantas Points

0.25 Qantas Points

12,500 Qantas Points

$0 annual fee in first year (then $89 thereafter)

19.49% p.a.

St.George Amplify Business Credit Card - Qantas points

0.25 Qantas Points

12,500 Qantas Points

$0 annual fee in first year (then $89 thereafter)

19.49% p.a.

Bank of Melbourne Amplify Business Credit Card

0.25 Qantas Points

12,500 Qantas Points

$0 annual fee in first year (then $89 thereafter)

19.49% p.a.

Card info per Money.com.au’s credit cards database as at 21 October 2026 and subject to change. The table is sorted by highest to lowest points earn rate available for ATO spending, then annual fee highest to lowest.

Can you earn credit card points on tax payments?

If your credit card allows you to earn rewards points on ATO spending, you’ll be able earn rewards points on your tax bill, but only until 30 June 2027. Beyond that date, the ATO will no longer be accepting credit card payments.

Just bear in mind that virtually all personal credit cards, with the exception of Amex cards, do not offer points on ATO spending. It’s much more commonly allowed on business credit cards.

But if your card does allow you to earn points on ATO spend, the benefit is that until 30 June 2027 you’ll be able to earn points without having to pay a card surcharge.

This situation arose following the Reserve Bank of Australia’s surcharge ban that came into effect on 1 October 2026. Hot on the heels of the surcharge ban, the ATO announced it would stop accepting credit card payment from 1 December 2026. But following backlash from small business owners, the Treasurer intervened and effectively forced the ATO to delay the credit card ban until the end of this financial year.

But because surcharges are now banned, there’s a rare window for taxpayers to pay their bill on a credit card surcharge-free, while earning points if their credit card allows it.

The window of opportunity...
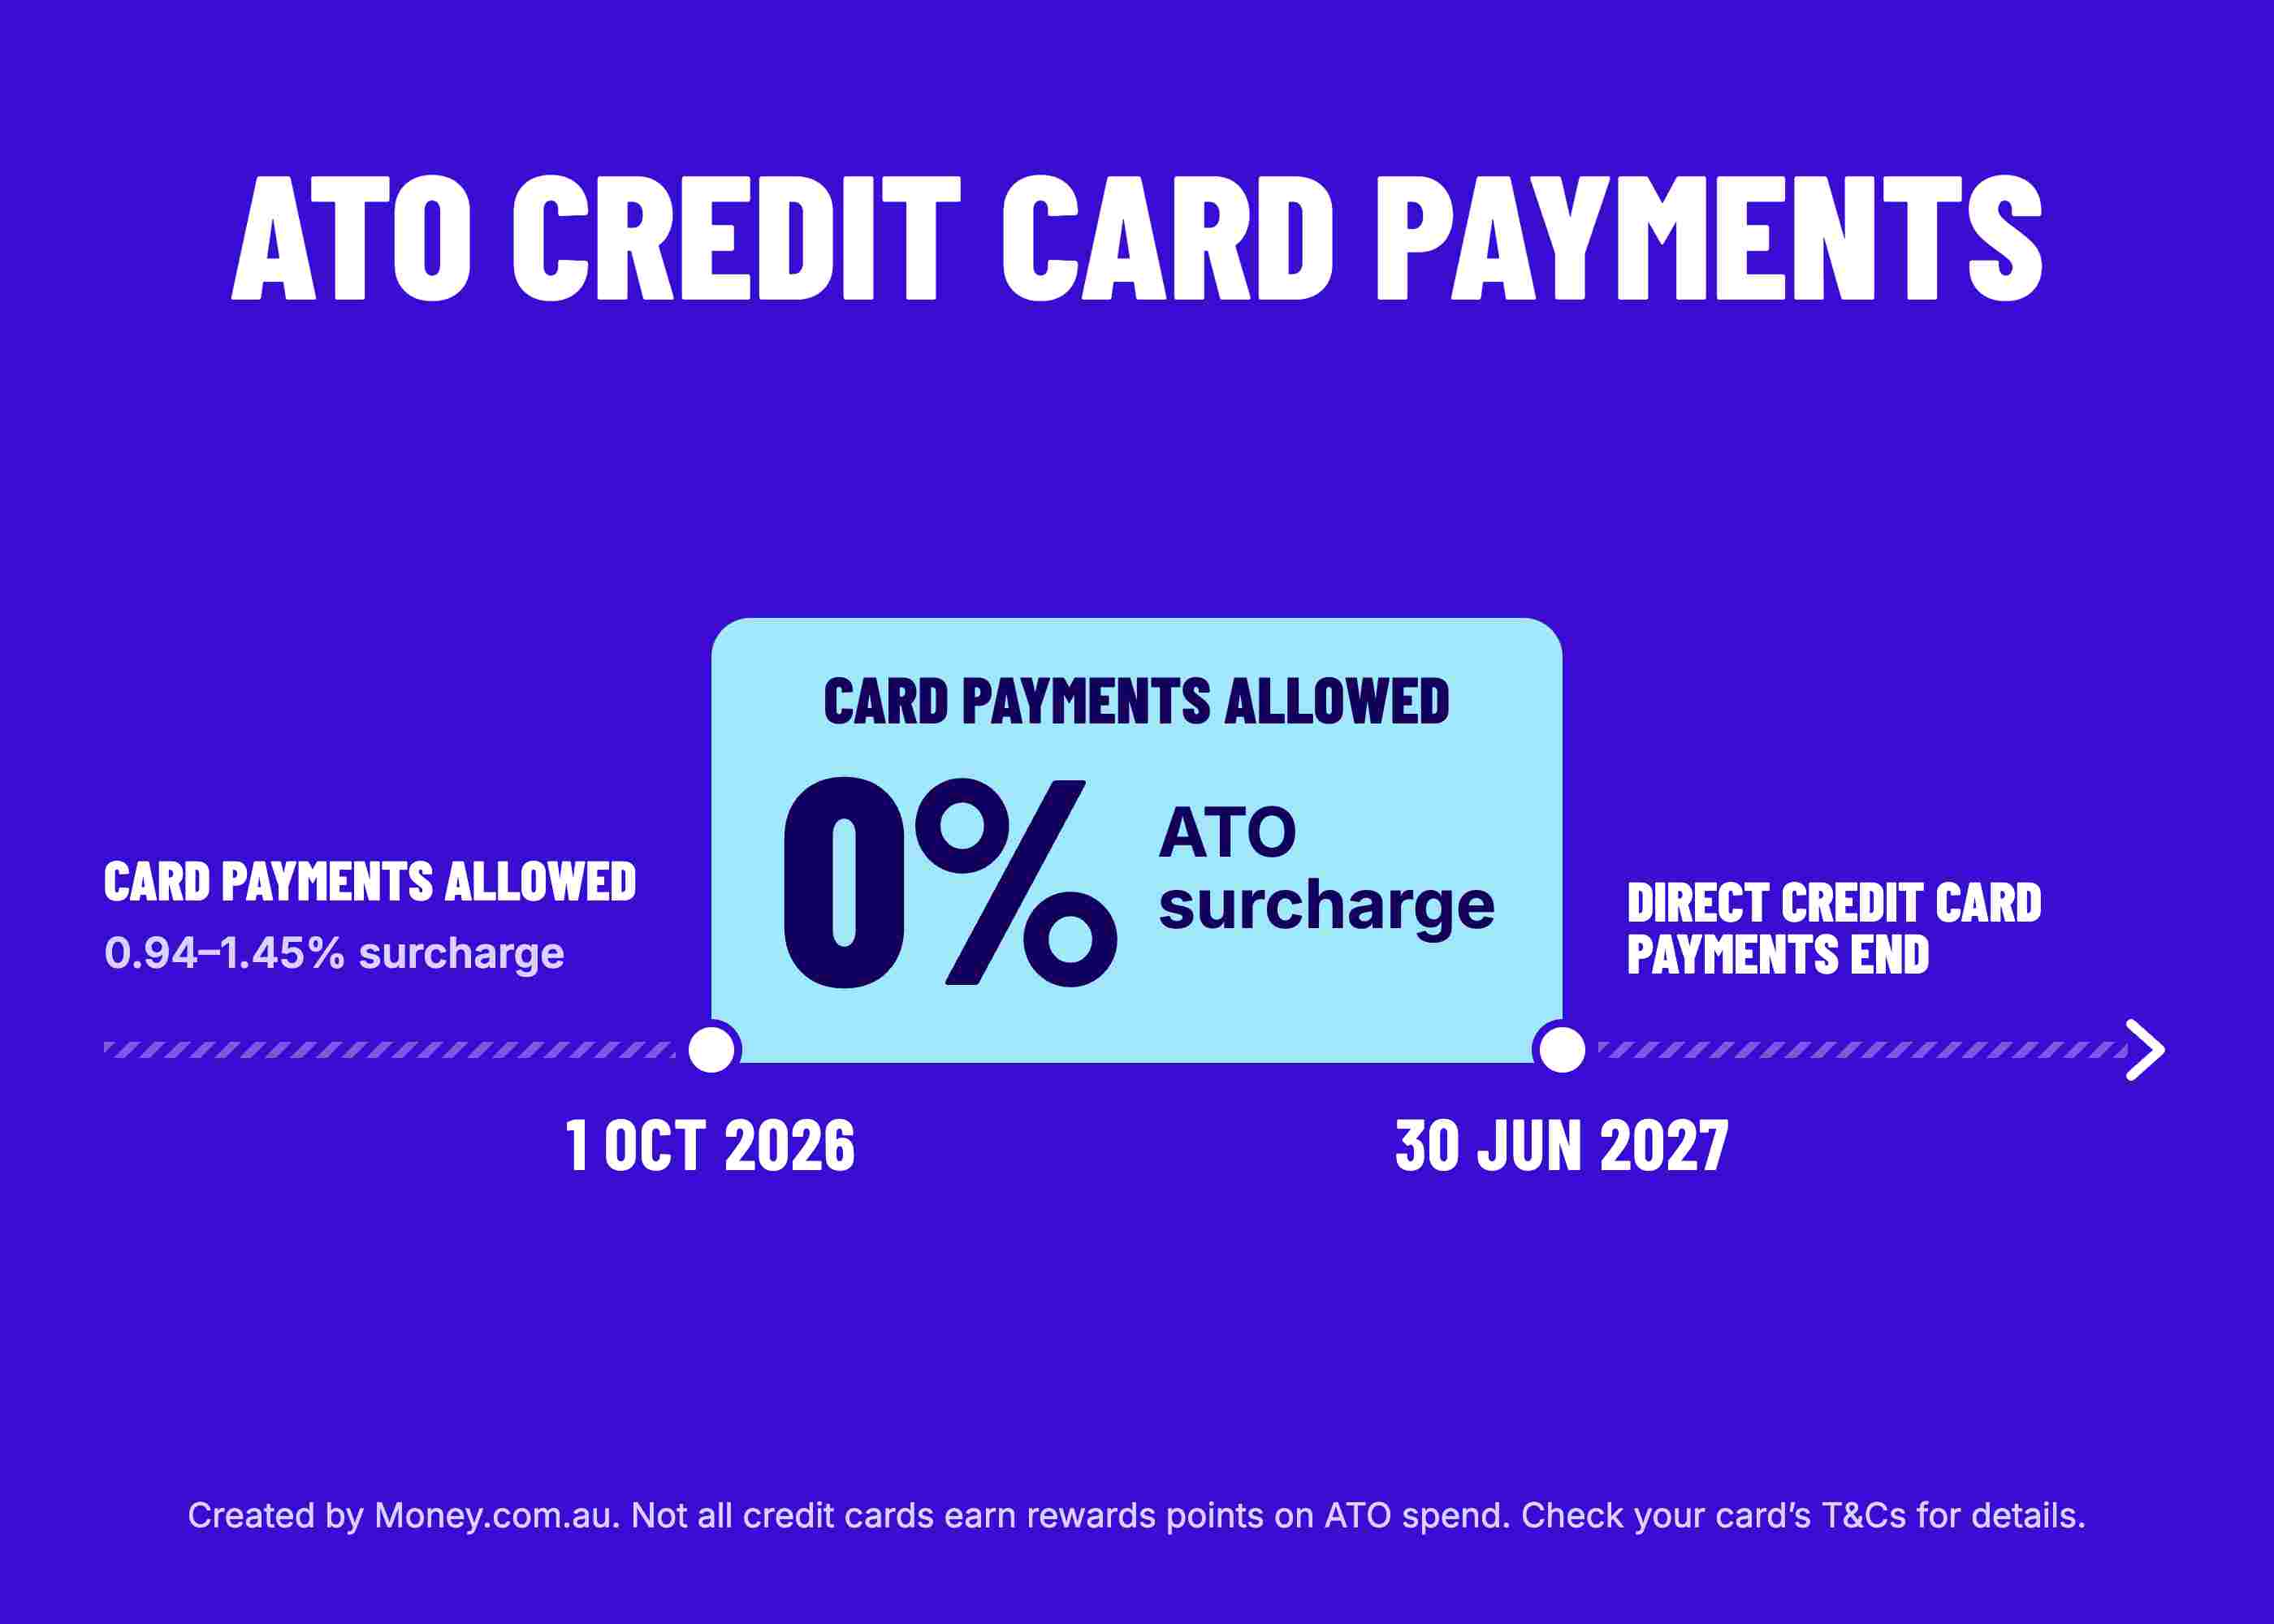
Timeline of ATO credit card payments: until 30 September 2026, card payments are allowed with a 0.94–1.45% surcharge; from 1 October 2026 to 30 June 2027, card payments are allowed with a 0% ATO surcharge; from 1 July 2027, direct credit card payments end.

Will there be a way to earn points on ATO spending beyond 1 July 2027?
Sean Callery, Editor of Money.com.au

Sean Callery, Editor of Money.com.au

"After the ATO stops allowing credit card payments, it may still be possible to earn rewards points by paying your tax bill via a third-party platform. But there are typically provider fees involved if you want to do this, which puts a major dent in the benefit you ultimately get through the points."

Sean Callery, Editor of Money.com.au
Prior to the surcharge ban, more than a quarter of Australians (27%) planned to increase their credit card spending or bring forward purchases to earn points before the rewards were slashed, according to Money.com.au’s survey of over 1,000 Australians from July 2026.

What to consider when choosing a credit card to pay tax

coins-hand

1. Will you get enough value before the ATO stops accepting cards?

Remember, there’s a very limited window during which the ATO is actually accepting credit card payments. After 30 June 2027, how good or bad your credit card is for earning points on ATO spend will be completely irrelevant. In other words, if you’re shopping for a credit card, make sure it’s suitable for you beyond the tax payment considerations.

coins-swap-02

2. The earn rate for tax payment

If credit card providers do allow card holders to earn points on ATO spend, then generally a separate lower earn rate applied versus what you get on everyday spending. Check that the government spending earn rate is high enough to make it worth your while.

Credit card check icon

3. The amount of money owed to the ATO

The number of points you’ll earn will naturally also depend on how much your ATO bill will cost. If it’s a small bill, consider whether the points you’ll earn will make a meaningful difference. If you're expecting a large bill, make sure your credit card limit will be high enough to cover it.

Percent 3 svg

4. The card’s interest rate and fees

Rewards credit cards tend to have higher interest rates than other card options. So, if you're not planning to pay off the card during the interest free-period, any interest paid will wipe the rewards benefit fast. The same goes for high annual or monthly card fees.

Money.com.au’s analysis shows that the average ATO spending earn rate on rewards credit cards is significantly lower than the everyday earn rate. On average, for personal reward credit cards the ATO earn rate is 0.69 points per $1 spent compared to the median everyday rate of 1.31 points. Similarly, business credit cards earn an average of 0.74 points per $1 spent, and have an average everyday rate of 1.08 points.

How to earn points by paying taxes with a credit card

There are three approaches you can take to paying your taxes with the ATO, as listed below. Some credit card providers could require that you use a certain method to pay, otherwise you may be in the habit of paying a particular way.

  1. Pay the ATO directly through myGov

    Navigate to the ATO section of your myGov account and follow the pathway until the ‘Payment Options’ section then select the card payment option and enter your credit card’s details.

  2. Pay through the Government’s EasyPay service

    Go to the Government’s EasyPay website and make a payment by entering your Payment Reference Number (PRN), the amount you're paying and your credit card details.

  3. Pay through a bill payment service

    There are also some services that let people pay bills, including taxes, with a credit card even if the biller doesn’t accept credit card payments. These include, Sniip, B2Bpay and RewardPay which are available for both personal and business use and allow cardholders to earn rewards points at the full everyday rate, rather than the reduced rate for government spending. To use these services, you’ll have to sign up for an account, save your card information and it will typically charge a processing per transaction fee depending on the payment method you use.

Pros and cons of paying tax with a credit card

Pros

    greenTickCircle
  • Earning rewards on a large expense that you would have had to pay anyway
  • greenTickCircle
  • Could count towards an eligible purchase for a sign up bonus
  • greenTickCircle
  • May help to manage cash flow by giving additional time between paying your tax bill and repaying the card’s balance

Cons

    redCrossCircle
  • Interest rates on reward credit cards are high
  • redCrossCircle
  • It’s not a long term opportunity as the ATO’s credit card ban starts 30 June 2027
  • redCrossCircle
  • Recent changes to rewards programs have seen points redemption value decrease

Is earning points on tax payments worth it?

For a short period of time, select reward credit card holders can earn points on ATO payments without having to pay surcharges. If you already have a credit card that earns you rewards points on ATO spend, happy days.

However, whether it's worthwhile signing up for a credit card based on its government spending earning potential is a different story and depends on your individual situation.

Previously, card surcharges considerably diminished the value of earning points on ATO spend as you’d be paying an extra 1.45% for payments made using an Amex card, 0.94% on a domestic Mastercard credit card and 0.98% on a domestic Visa credit card.

But in the current window up until 30 June 2027, the lack of a surcharge removes the biggest downside to using a rewards credit card to pay the ATO.

For example, a business owner with a tax bill of $60,000 that has an American Express card earning 1 Membership Rewards Point per dollar on ATO payments would earn 60,000 points from paying their tax bill. Prior to the RBA’s surcharge ban, this payment would’ve incurred a surcharge of 1.45% or approximately $870.

But there are other costs to consider when using a rewards credit card, including high purchase rates, annual fees, as well as over-the-limit and late payment fees, that make weighing up the benefits and the cost essential.
Your questions answered

The ATO is banning credit card payments as of 30 June 2027 to avoid having to pay the credit card processing fees that it had previously charged on card payments. This follows the RBA’s decision to remove the cost of surcharges from customer transactions.

Yes, while the ATO initially announced that its ban on credit card payments would start in December 2026, widespread criticism saw it rescheduled until 30 June 2027. The decision’s delay means that there’s a temporary period until that date where cardholders can pay tax by credit card without paying surcharges and still earn rewards points.

No, not all rewards credit cards earn points on government spending. The tables above show most of the credit cards where tax payments can accrue points. If you're uncertain whether your rewards card can earn points on paying taxes check online from the card provider’s website or get in contact with them.

This can change depending on the credit card issuer, but technically the ATO is a government body and expenses there are generally categorized under government spending. However, points may be awarded at the credit card provider's discretion, so it’s worthwhile checking with your card’s issuer if you're uncertain.

Isabella Visser is a Finance Writer with Money.com.au. With her experience in journalism and writing content across multiple platforms she makes finance simpler for readers by creating insightful and engaging content.
Sean Callery is the Editor of Money.com.au. He has over 15 years of international experience. He is qualified with a Certificate IV in Finance and Mortgage Broking (FNS40821) and is compliant to provide general advice in Tier 1 General Insurance (RG 146) products.

Important Disclosures

General information only

The information on this page is general in nature and has been prepared without considering your objectives, financial situation or needs. You should consider whether the information provided and the nature of the credit card product is suitable for you and seek independent financial advice if necessary.

We are not providing you with a recommendation or suggestion about a particular credit product. You should read the relevant disclosure statements or other offer documents before deciding whether to apply for or continue to hold a particular credit card.

What products, features and information are shown

While we make every effort to ensure all credit cards available in Australia are shown in our comparison tables, we cannot guarantee that all products are included. Where we become aware of a card that is missing from our tables, we commit to adding it within one business day.

Our product comparisons may not compare all card features and attributes relevant to you.

Product information, such as interest rates, fees and charges, is subject to change without notice. Before acting on any information, you should confirm the relevant product information with the card issuer. While we do our best to ensure the information provided on this website is accurate, all information on this website is provided without any representation or warranty, either express or implied, being given as to the accuracy, completeness, timeliness, reliability or otherwise of its content. No responsibility is accepted by us for any errors, omissions or any inaccurate information on this website.

How cards are sorted and filtered by default

Users can easily change the sort order and apply product filters to our product comparison tables. However, when you arrive on a page initially or select a particular card type via the ‘card features’, a default sort order is applied as follows:

  • Default sort (main credit card page): Consumer credit cards sorted by the highest number of reward points earned per $1 spent, then lowest ongoing annual fee, then alphabetically by provider/product name. Partner products are shown first and are ordered based on the sort criteria above, then all products are shown and are sorted based on the same criteria.
  • No annual fee cards: Consumer credit cards sorted by lowest ongoing annual fee, then the highest number of reward points earned per $1 spent, then alphabetically by provider/product name. Partner products are shown first and are ordered based on the sort criteria above, then all products are shown and are sorted based on the same criteria.
  • Low rate cards: Consumer credit cards sorted by lowest purchase rate, then lowest ongoing annual card fee, then alphabetically by provider/product name. Partner products are shown first and are ordered based on the sort criteria above, then all products are shown and are sorted based on the same criteria.
  • Balance transfer cards: Consumer credit cards sorted by lowest balance transfer rate, then longest duration of BT offer, then lowest ongoing annual card fee, then alphabetically by provider/product name. Partner products are shown first and are ordered based on the sort criteria above, then all products are shown and are sorted based on the same criteria.
  • Rewards and frequent flyer cards: Consumer credit cards sorted by highest rewards/FF points per dollar earned on everyday purchases, then lowest ongoing annual card fee, then lowest purchase rate, then alphabetically by provider/product name. Partner products are shown first and are ordered based on the sort criteria above, then all products are shown and are sorted based on the same criteria.
  • Cashback cards: Consumer credit cards sorted by highest cashback per dollar earned, then lowest ongoing annual card fee, then lowest purchase rate, then alphabetically by provider/product name. Partner products are shown first and are ordered based on the sort criteria above, then all products are shown and are sorted based on the same criteria.
  • Interest-free cards/offers: Consumer credit cards sorted by longest 0% purchase rate offer period, then lowest ongoing purchase rate, then lowest ongoing annual card fee, then alphabetically by provider/product name. Partner products are shown first and are ordered based on the sort criteria above, then all products are shown and are sorted based on the same criteria.
  • Credit cards with lounge access: Consumer credit cards sorted by highest number of free lounge passes, then lowest to highest ongoing annual card fee, then highest to lowest points per dollar earned on everyday spending, then lowest purchase rate, then alphabetically by provider/product name. Partner products are shown first and are ordered based on the sort criteria above, then all products are shown and are sorted based on the same criteria.
  • No international fee cards/cards with travel insurance: Consumer credit cards sorted by lowest ongoing annual card fee, then highest points per dollar earned on everyday spending, the lowest purchase rate, then alphabetically by provider/product name. Partner products are shown first and are ordered based on the sort criteria above, then all products are shown and are sorted based on the same criteria.
  • Business credit cards/charge cards: Business cards sorted by highest points per dollar earned on everyday spending, then lowest ongoing annual card fee, then lowest ongoing purchase rate, then alphabetically by provider/product name. Partner products are shown first and are ordered based on the sort criteria above, then all products are shown and are sorted based on the same criteria.

We may earn a commission from product providers if you are issued with a credit card via a link from this page. Cards marked as ‘sponsored’ are not selected or positioned on the page solely based on their product attributes. In our comparison tables, products are displayed based on the relevant default sort order and filters applied for that card type, or the sort order and filters selected by a user. We may earn a commission if you are issued with a card via a link from our comparison tables.